Email us today!
Your teenager just got a license, your spouse moved in, or an aging parent now lives under your roof. Each of these situations triggers the same obligation under Michigan law: you must update your auto insurance policy. Michigan treats household members differently than most states because of its unique no-fault system, and the financial consequences of getting this wrong can be severe. A single uninsured household member can give your carrier grounds to deny an entire claim, even if that person was not behind the wheel at the time of the accident.
The average annual cost for full coverage auto insurance in Michigan already sits around $3,824 as of mid-2026, placing the state among the most expensive in the country. Adding a household driver, especially one with limited experience or a spotty record, can push that figure significantly higher. Understanding how auto insurance changes after adding a household driver in Michigan is not just a budgeting exercise. It is a matter of legal compliance and financial protection for your entire family.
This guide walks through the rules, the real costs, and the specific strategies Michigan families can use to keep premiums manageable without sacrificing coverage.
Understanding Michigan's Household Member Rule
Michigan insurance law requires that every person residing in your household be disclosed to your auto insurer. This rule exists because Michigan's no-fault system provides benefits to household members regardless of who caused an accident. Your insurer needs an accurate picture of who lives with you to price your policy correctly and to determine coverage obligations.
Who Counts as a Household Resident?
The definition is broader than many families expect. A household resident is any person who lives in your home on a regular basis, even if they do not share your last name or appear on your lease. Adult children who return home after college, a partner who stays most nights of the week, or a grandparent who has moved in for long-term care all qualify. Temporary guests, such as someone visiting for a few weeks, generally do not meet the threshold. The key factor is whether the person treats your address as their primary residence.
The Legal Requirement to List All Drivers
Michigan insurers are entitled to know about every licensed driver in your household, and you are contractually required to disclose them. Failing to list a household driver is not simply an oversight. It can be treated as a material misrepresentation on your policy, which gives the insurer grounds to rescind coverage entirely. If an unlisted household member causes an accident, your carrier may deny the claim and leave you personally liable for damages, medical bills, and legal costs.
By: John G. Growney
President of Oakland Insurance
How New Drivers Impact Your No-Fault Coverage
Michigan's no-fault system provides a distinct set of benefits that change in scope and cost when you add someone to your policy. The impact depends on the type of coverage and the risk profile of the new driver.
PIP Medical Coverage for Household Members
Personal Injury Protection is the cornerstone of Michigan's no-fault system. Every household member is covered under your PIP selection, whether they are listed on the policy or not. That said, your PIP premium is recalculated when you add a driver because the insurer is now accounting for the medical risk of an additional person. Michigan's Department of Insurance and Financial Services announced a 16.38% increase to the auto medical fee schedule for the 2026-2027 period, which means PIP-related costs are already climbing before you factor in a new household member.
Liability Limits and Risk Assessments
Your liability coverage protects you when someone on your policy causes harm to another person or their property. Adding a driver with a clean record may produce only a modest increase. Adding a young driver with no history, or an older driver with past claims, can trigger a significant rate adjustment. Insurers run motor vehicle reports and may also pull credit-based insurance scores to assess the new risk. The result is a recalculated premium that reflects the combined driving profiles of everyone on the policy.
Comparing Costs: Adding a Driver vs. Separate Policies
Many families wonder whether it is cheaper to add a new driver to an existing policy or to purchase a separate policy for that person. In most Michigan scenarios, adding the driver to your current policy costs less.
| Factor | Adding to Existing Policy | Separate Policy |
|---|---|---|
| Multi-car/multi-driver discounts | Yes, usually applied | Not available |
| PIP coverage | Shared under one selection | Must purchase independently |
| MCCA assessment | One per household | Duplicate per policy |
| Administrative simplicity | Single renewal, single bill | Separate renewals and billing |
| Premium flexibility | Bundled discount potential | Higher base rate for young/new drivers |
A separate policy for a young or inexperienced driver almost always costs more because that person cannot benefit from the established policyholder's history and bundled discounts. The exception is when the new household member has such a poor driving record that adding them would raise the entire household's premium beyond what a standalone policy would cost.
What Adding a Teen Driver Really Costs in Michigan
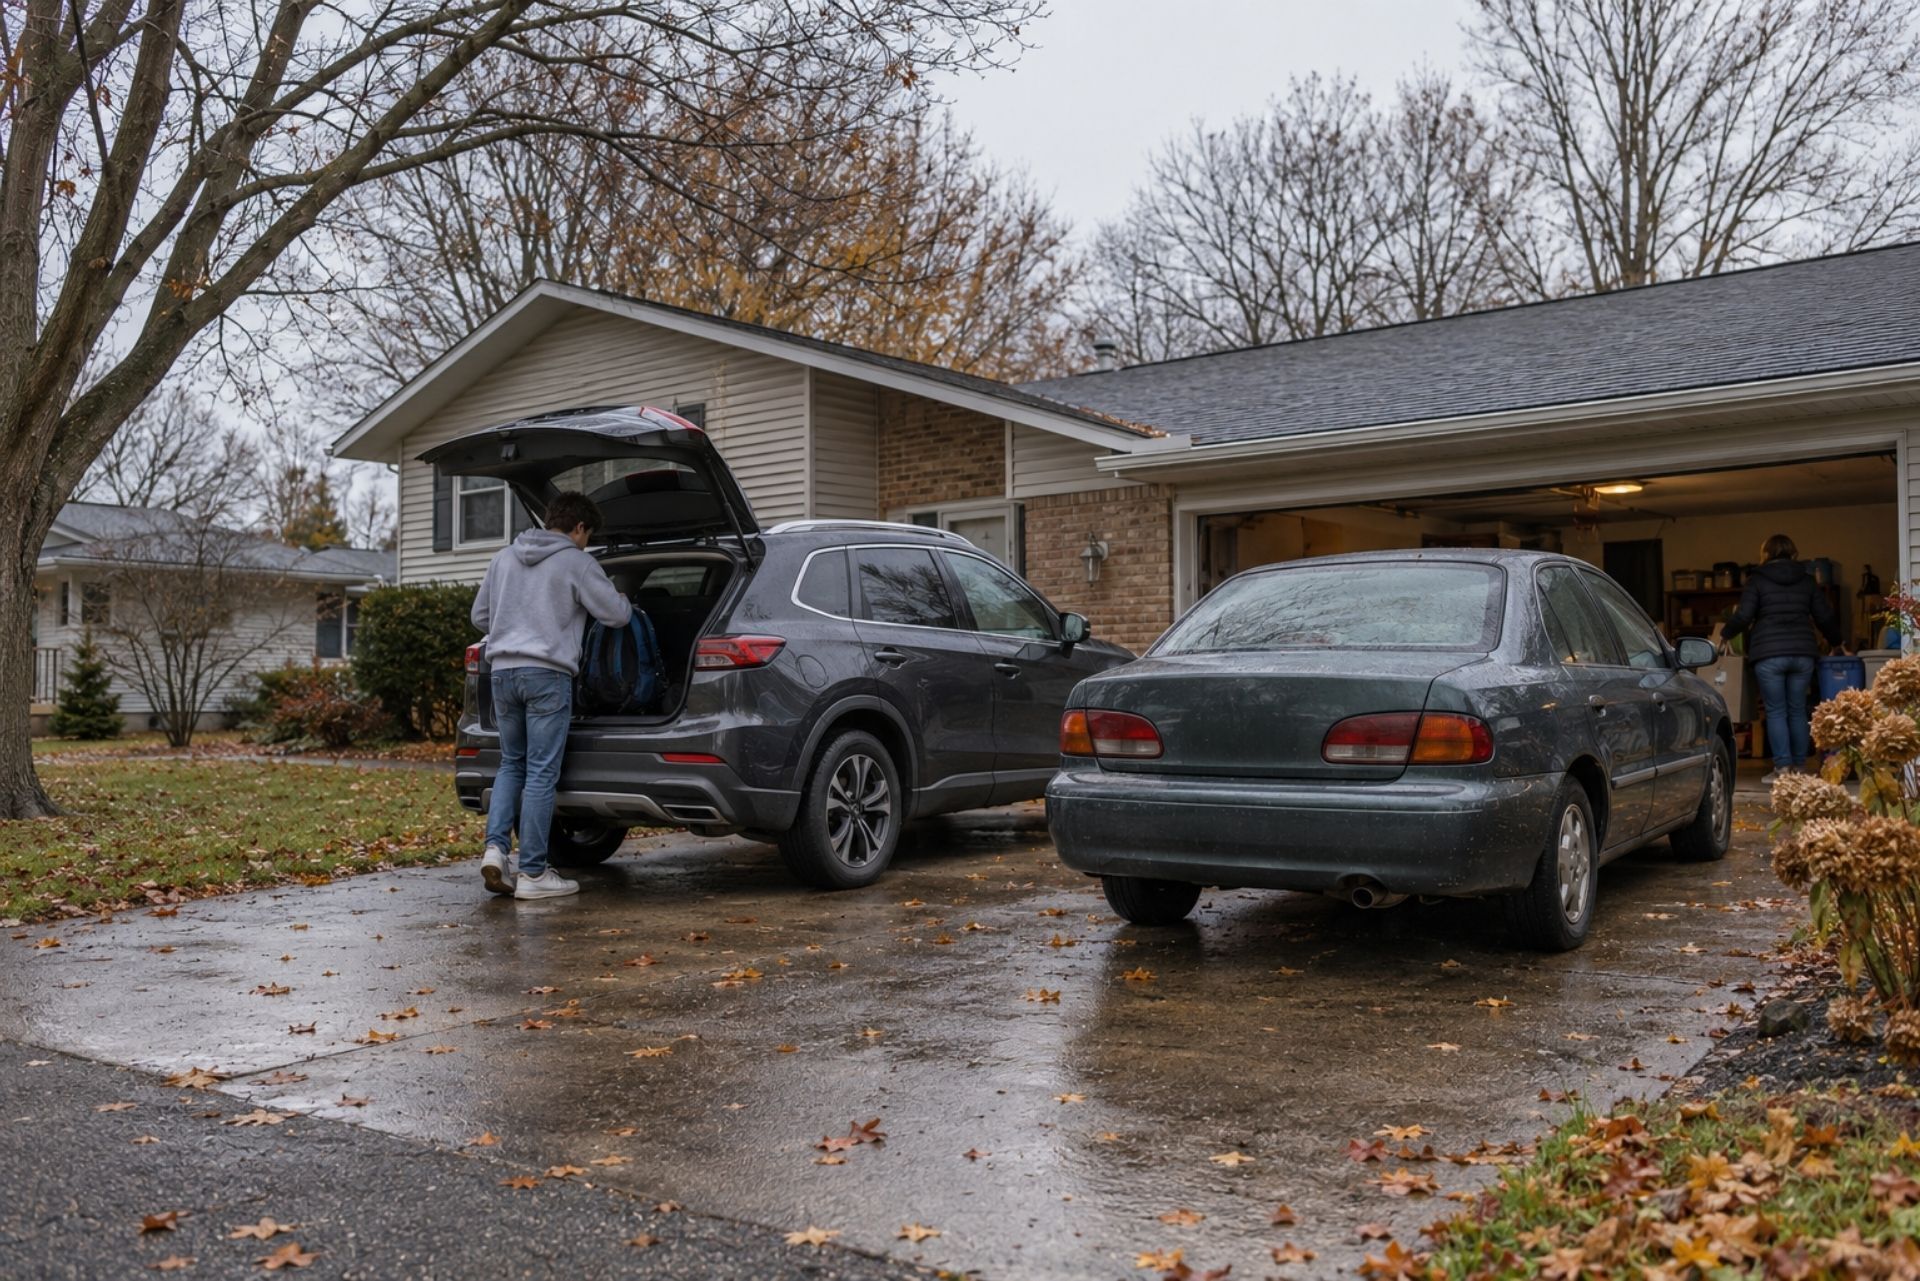
Teen drivers represent the single largest rate increase most Michigan families will face. Insurance for a 16-year-old in Michigan can add $3,000 to $5,000 or more per year to a family policy, depending on the vehicle, coverage levels, and the teen's gender. That figure often shocks parents who are already paying some of the highest premiums in the nation.
The reason is straightforward: teen drivers are statistically the most likely age group to be involved in accidents. Michigan insurers weigh this risk heavily. A family paying $3,824 annually could see their total premium jump to $6,500 or more after adding a 16-year-old. The specific vehicle assigned to the teen matters as well. Placing a teen on an older sedan with good safety ratings will cost less than listing them on a newer SUV or a sports car. Families who
plan ahead for this expense can soften the blow by shopping carriers and adjusting deductibles before the teen earns their license.
Rate increases after adding a household driver are not entirely out of your control. Several strategies can reduce the financial impact without leaving your family underinsured.
Student Discounts and Good Driver Rewards
Most Michigan insurers offer a good student discount for drivers under 25 who maintain a B average or higher. This discount typically ranges from 5% to 15% off the young driver's portion of the premium. Some carriers also offer discounts for completing a state-approved driver education course. Good driver rewards for experienced household members, such as accident-free discounts or low-mileage credits, can offset part of the increase caused by adding a higher-risk driver.
Utilizing Named Driver Exclusions
If a household member does not need to drive any of your vehicles, Michigan allows you to file a named driver exclusion. This formally removes that person from coverage, meaning the insurer will not pay any claims arising from their operation of your vehicles. The trade-off is absolute: if the excluded person drives your car and causes an accident, you have zero coverage. Named driver exclusions work well for household members who have their own separate policy or who do not drive at all. They should never be used as a cost-cutting shortcut for someone who occasionally borrows your car.
Common Questions About Michigan Driver Updates
You should notify your insurer as soon as a new person moves into your household or as soon as a household member obtains a driver's license. Most carriers require notification within 30 days. Waiting longer risks a coverage gap or a disputed claim.
A common question is whether you can delay adding a teen driver until they actually start driving regularly. The answer is no. Michigan law and most policy contracts require disclosure when the person becomes a licensed household resident, not when they first borrow the car. Another frequent concern involves roommates. If you share a home with someone who is not a family member, your insurer still needs to know about them if they have a license, even if they have their own vehicle and their own policy.
How Michigan's No-Fault Reforms Affect Your Updated Policy
Michigan's 2019 no-fault reform law continues to shape premiums in 2026. Before the reform, every Michigan driver was required to carry unlimited lifetime PIP medical coverage, which drove premiums to some of the highest levels in the country. The reform introduced tiered PIP options, allowing drivers to choose coverage levels ranging from $50,000 to unlimited.
When you add a household driver, your chosen PIP tier applies to that person as well. Families selecting lower PIP levels have seen meaningful savings, but the MCCA assessment, which funds catastrophic claims, still applies. The
2026-2027 MCCA assessment remains well below pre-reform levels, which is welcome news for households absorbing the cost of an additional driver. Reviewing your PIP tier when adding a driver is a smart move, as your coverage needs may have changed since you last selected a level.
The process itself is straightforward, but getting the details right matters.
- Gather the new driver's full legal name, date of birth, driver's license number, and Social Security number.
- Contact your insurance agent or carrier directly. Most allow updates by phone, online portal, or through a local agent's office.
- Provide information about which vehicle the new driver will primarily operate. This affects how the premium is calculated.
- Ask for a revised declarations page showing the updated driver list and new premium amount.
- Review the revised policy carefully. Confirm that PIP, liability, and collision coverage levels are correct for the expanded household.
- Pay any adjusted premium amount. Most carriers prorate the increase from the date the driver is added.
Keeping a copy of your updated declarations page in each household vehicle is a practical step that can prevent confusion during a traffic stop or after an accident.
Mistakes Families Make When Adding Drivers to Michigan Policies
The most costly mistake is simply not disclosing a new household driver. Families sometimes assume that a college student living away from home does not need to be listed, but most insurers consider a student under 24 who maintains your address as their permanent home to be a household resident. Failing to list them can void your coverage entirely.
Another common error is automatically assigning the new driver to the most expensive vehicle on the policy. Strategically assigning a teen or new driver to the vehicle with the lowest value and best safety record can reduce the premium increase. Families also overlook the opportunity to shop around. Adding a driver is a qualifying life event that gives you a natural reason to compare quotes from multiple carriers. Michigan's market is competitive enough that
rate differences between carriers can be substantial for the same household profile.
Frequently Asked Questions
Do I have to add my spouse to my auto insurance in Michigan? Yes. Michigan requires that all licensed household residents be disclosed to your insurer. Your spouse qualifies as a household resident, and failing to list them could result in a denied claim.
Can I remove a household member from my policy if they have a bad driving record? You can file a named driver exclusion, which removes them from coverage. That person will have zero coverage under your policy if they drive your vehicle, so this option should only be used when the excluded driver has their own separate insurance or does not drive.
Will adding a driver with a DUI raise my rates significantly? Yes. A DUI on a household member's record can increase your premium by 50% to 100% or more, depending on the carrier and the recency of the offense. Some insurers may decline to add the driver altogether.
How long does a teen driver affect my premium? The most significant rate impact lasts until the driver turns 25 and builds a clean driving history. Rates typically decrease each year as the young driver gains experience and avoids accidents or violations.
Does Michigan require uninsured motorist coverage when I add a driver?
Michigan does not mandate uninsured motorist coverage, but it is strongly recommended. Your insurer must offer it, and you must sign a written rejection if you choose not to carry it.
Making the Right Choice for Your Family
Adjusting your auto insurance after adding a household driver in Michigan is both a legal requirement and a financial decision that deserves careful attention. The state's no-fault system, combined with some of the highest premiums in the country, means that every coverage choice carries real dollar consequences.
Start by disclosing the new driver promptly and accurately. Then review your PIP tier, vehicle assignments, and available discounts to find the most cost-effective configuration. Shopping multiple carriers is one of the most effective ways to control your Michigan auto insurance costs, especially after a household change that shifts your risk profile.
Your next step should be a conversation with a licensed Michigan insurance agent who can review your specific household situation. An experienced agent will identify discounts you may not know about, flag coverage gaps, and help you structure a policy that protects your family without overpaying. Do not wait until renewal. The sooner you act, the sooner you are properly covered and compliant with Michigan law.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying