Email us today!
Picture a snowy January morning on I-96 near Novi, where a minivan slides through a red light and strikes the passenger side of your Ford Explorer while your children sit in the second row. In that moment, the quality of your insurance policy matters far more than the price you paid for it, and Michigan's unique auto insurance system determines who pays for medical care, vehicle repairs, and potential lawsuits.
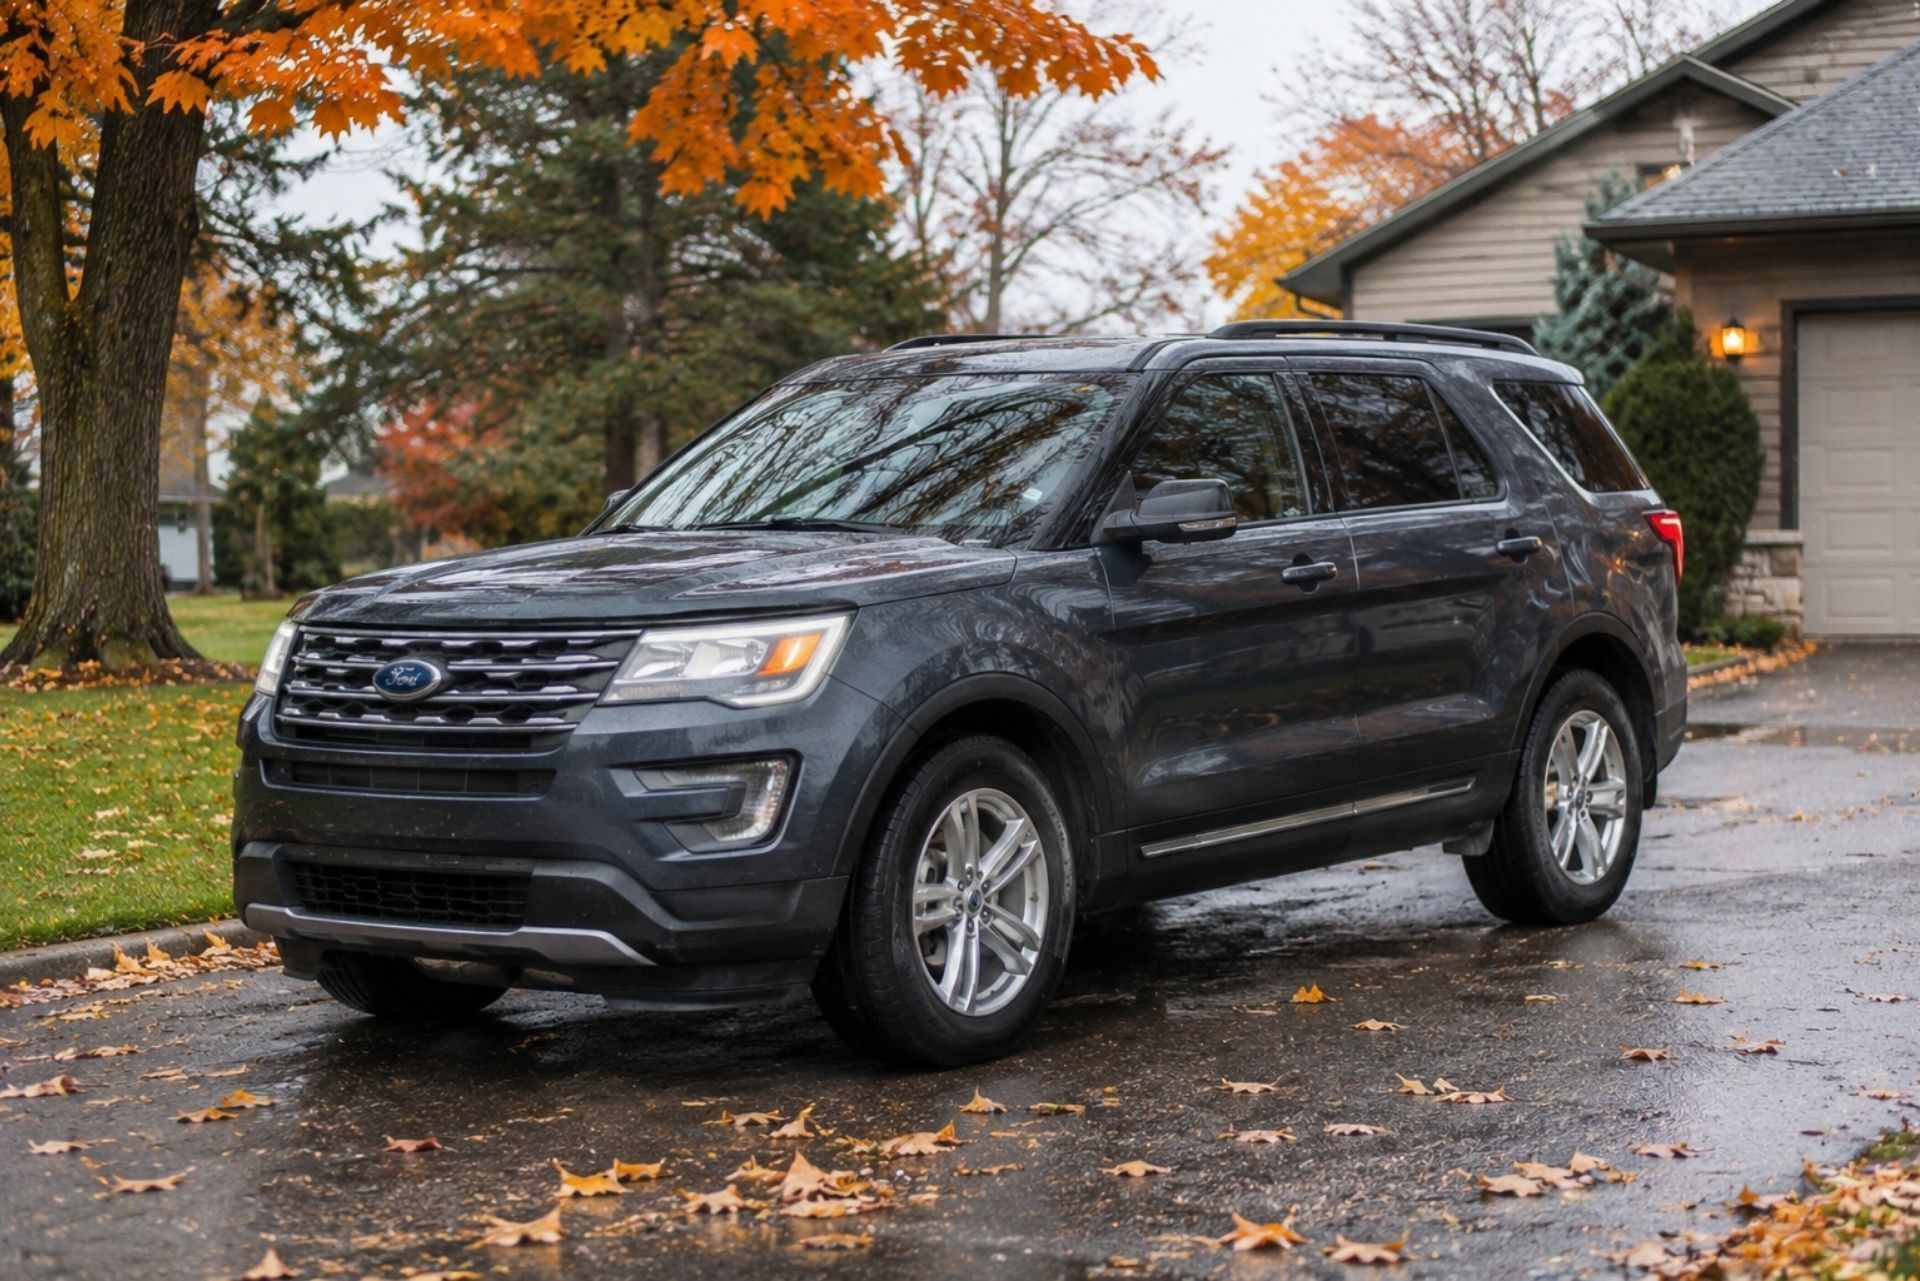
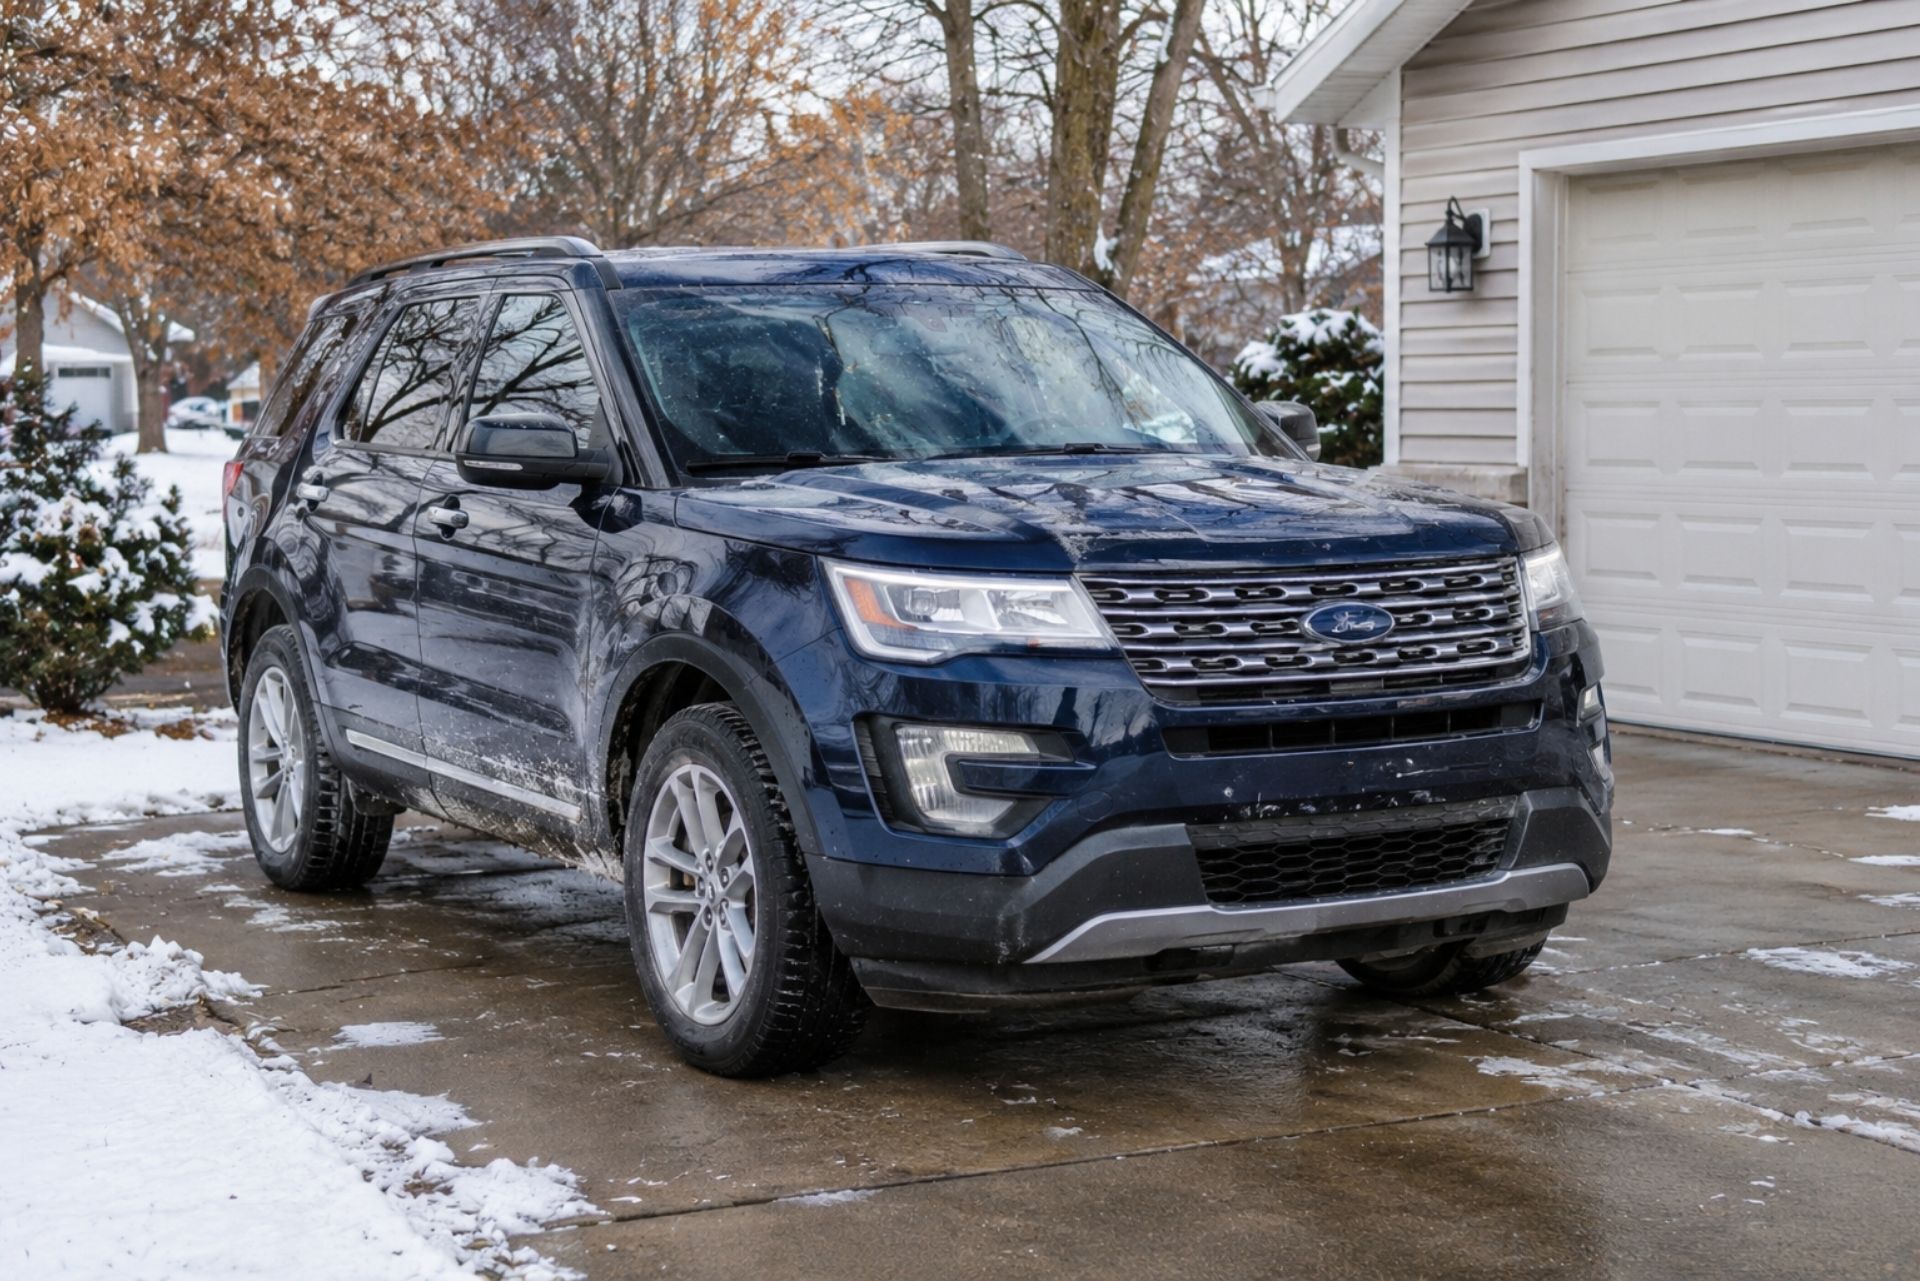
The Ford Explorer has long been one of the most popular family SUVs on Michigan roads, from the suburbs of Ann Arbor to the lake towns of the northern Lower Peninsula. Its three-row seating, available all-wheel drive, and towing capacity make it a practical choice for Michigan families who travel in every season. Those same strengths, however, create specific insurance considerations that deserve careful attention.
This guide to Ford Explorer auto insurance in Michigan explains how no-fault rules, personal injury protection choices, physical damage coverage, deductibles, and discounts work together for a family SUV. You will also find a coverage comparison table, answers to common questions, and practical steps for building a tailored policy that protects both your passengers and your finances without paying for coverage you do not need.
Insuring the Ford Explorer in Michigan: What You Need to Know
The Ford Explorer occupies a distinct position in the insurance market because it combines family-oriented use with a relatively high replacement value and sophisticated electronics. Insurers evaluate the Explorer based on repair costs, injury claim history, theft exposure, and the advanced technology built into recent model years. For Michigan Explorer owners, these vehicle factors combine with one of the most complex state insurance systems in the country.
Several characteristics shape how carriers price and cover the Explorer:
- Three-row seating: More occupants means greater potential exposure for injury claims, which affects how you should think about PIP and liability limits.
- Advanced driver assistance systems: Cameras, radar sensors, and parking assist features can reduce accidents, yet they raise repair costs when damage does occur.
- Towing and recreational use: Many Michigan families tow boats or campers to Traverse City, Houghton Lake, or the Upper Peninsula, which raises questions about trailer coverage.
- Winter driving exposure: Lake-effect snow, black ice, and deer collisions create year-round physical damage risks across the state.
One thing to keep in mind is that the repair bill for a modern Explorer often extends beyond sheet metal and paint. Industry data indicates that ADAS technology has increased claim severity by roughly 42.3% since 2020, largely because of specialized parts and data access requirements. If you own a recent Explorer, your coverage choices should reflect that reality, and a licensed Michigan agent can help you review a tailored quote that accounts for your specific model year and trim.
By: John G. Growney
President of Oakland Insurance
Understanding Michigan No-Fault Laws and Your Explorer
Michigan operates under a no-fault system, which means your own auto insurance policy generally pays for your medical expenses after an accident regardless of who caused the crash. This structure differs from tort states, where the at-fault driver's insurer typically covers injuries for everyone involved. For Michigan Explorer owners carrying family members, the no-fault framework places significant responsibility on your own policy selections.
The 2019 reform of Michigan's no-fault law, which took effect in 2020, gave drivers far more choice over their coverage than they had previously. Before reform, every Michigan driver carried unlimited lifetime medical benefits, which contributed to some of the highest premiums in the nation. Today, you can choose among several PIP levels, and those choices directly affect both your premium and your protection.
The mandatory components of a Michigan auto policy include personal injury protection, property protection insurance, and residual bodily injury and property damage liability. Understanding each component helps you avoid gaps that commonly surprise families after a serious crash. The subsections below explain how each piece applies to your Explorer, and your agent can walk you through each option during a personalized consultation.
The Role of Personal Injury Protection (PIP) Choices
Personal injury protection covers medical expenses, a portion of lost wages, and replacement services for you, your household family members, and certain passengers after an accident. Because the Explorer frequently carries children, grandparents, and carpool passengers, your PIP decision carries real consequences.
Michigan now permits drivers to select from multiple PIP medical tiers, ranging from unlimited coverage down to lower limits and, for certain qualifying drivers, an opt-out option. Drivers with qualified health coverage may choose a $250,000 PIP medical option with exclusions to reduce premium costs. The catch is that excluded household members must have their own qualifying health coverage or other auto coverage in place.
A common client mistake involves selecting a lower PIP tier without confirming whether every household member's health plan actually qualifies. If a teenage driver or elderly parent lacks qualifying coverage, that gap can become extremely costly after a serious injury on a Michigan highway.
Residual Liability and Property Protection Insurance
Residual bodily injury liability protects you if you seriously injure someone and face a lawsuit, or if you cause an accident outside Michigan. Even under no-fault rules, injured parties can sue for pain and suffering when injuries meet certain thresholds, and they can pursue excess medical costs beyond their own PIP limits.
Property protection insurance, known as PPI, covers damage your Explorer causes to other people's property within Michigan, such as buildings, fences, and legally parked vehicles. This matters because the Explorer's size and weight can cause substantial damage to structures in a low-speed parking lot incident.
Since the reform, carriers set default liability limits that are higher than the previous state minimums, and you must sign a specific form to select lower limits. Given the medical cost exposure that now exists in Michigan, most advisors recommend carrying liability limits at or above the default levels, especially if you
own a home or have meaningful savings to protect.
Protecting Your SUV with Collision and Comprehensive Coverage
Collision and comprehensive coverage protect the Explorer itself, and neither is required by Michigan law. Your lender or leasing company will almost certainly require both if you finance or lease the vehicle, however, and most owners of newer Explorers choose to carry them regardless.
Collision coverage pays to repair your Explorer after it strikes another vehicle or object, or after a rollover. Comprehensive coverage handles non-collision losses, which are especially relevant in Michigan:
- Deer strikes: Michigan consistently ranks among the states with the most deer-vehicle crashes, particularly in October and November.
- Hail and windstorms: Summer storms can damage roofs, hoods, and glass across large areas in a single afternoon.
- Theft and vandalism: Catalytic converter and parts theft remain concerns in urban and suburban areas.
- Windshield damage: Gravel trucks and winter road debris frequently crack glass on Michigan freeways.
Windshield claims deserve special attention for Explorer owners. Many recent models mount forward-facing cameras behind the windshield, and specialized recalibration after windshield or bumper repairs can add over $1,000 to a standard repair bill. A cracked windshield that once seemed like a minor inconvenience can now become a significant claim, which is why comprehensive deductible selection matters so much for a technology-equipped family SUV.
Broadened vs. Standard Collision in Michigan
Michigan carriers typically offer several collision options, and the differences can significantly affect what you pay out of pocket after a crash. Standard collision pays for damage to your Explorer regardless of fault, minus your deductible. Broadened collision also pays regardless of fault, but it waives your deductible when you are not substantially at fault for the accident.
Many carriers also offer a limited collision option, which pays only when you are not substantially at fault and does not cover accidents you cause. Michigan's mini-tort provision allows you to recover a limited amount from an at-fault driver for vehicle damage, but that recovery rarely covers a full repair on a modern SUV. For most Explorer owners with newer vehicles, broadened collision provides the strongest balance of protection and value.
Comparing Michigan Coverage Levels for the Ford Explorer
The right package depends on the age of your Explorer, the size of your household, your health insurance situation, and your financial assets. The following comparison illustrates how three common coverage approaches differ for a Michigan family SUV.
| Coverage Element | Basic Package | Balanced Package | Maximum Protection |
|---|---|---|---|
| PIP Medical | Lower tier or opt-out (if eligible) | $250,000 with qualifying health coverage | Unlimited |
| Bodily Injury Liability | Reduced limits (signed form) | Default limits | Higher limits plus umbrella |
| Property Protection (PPI) | Required | Required | Required |
| Collision | None or limited | Standard | Broadened |
| Comprehensive | None | Higher deductible | Lower deductible |
| Best Fit | Older, paid-off Explorer | Most families with good health plans | New Explorer, significant assets |
This matters because each package carries a different risk profile. The basic package minimizes premiums but leaves you exposed to both vehicle replacement costs and potential lawsuits. The maximum protection package costs more, though it provides the greatest financial security for families carrying several passengers regularly.
Most Michigan families find the balanced package to be a reasonable starting point, then adjust based on their specific circumstances. If you tow a boat or camper, ask your agent to confirm how liability extends to your trailer and whether the trailer itself needs separate physical damage coverage. A tailored review ensures your Explorer insurance matches how your family actually uses the vehicle.
Your deductible represents the amount you pay out of pocket before collision or comprehensive coverage begins paying. Raising your deductible lowers your premium, while lowering it increases your premium, and finding the right balance requires an honest look at your savings.
Choosing a $1,000 deductible instead of a $500 deductible can significantly impact premium costs, though it requires greater readiness to cover repair expenses yourself. For a family with a healthy emergency fund, the higher deductible often makes financial sense over several years of premium savings.
Consider these practical strategies for managing your Explorer's premium costs:
- Split your deductibles: Many carriers allow different collision and comprehensive deductibles, so you might carry a higher collision deductible and a lower comprehensive deductible to address deer and windshield claims.
- Review PIP annually: Changes in employment or health plans can affect your eligibility for lower PIP tiers.
- Drop collision on older vehicles: If your Explorer's market value has declined substantially, the premium may exceed the realistic payout.
- Maintain continuous coverage: Gaps in coverage typically lead to higher rates when you return to the market.
Here's what that means for you: the cheapest premium is not always the least expensive policy. A low premium paired with a high deductible and minimal PIP can become far more costly after a single serious claim, so review your deductible choices with a licensed agent before finalizing your policy.
Available Discounts for Ford Explorer Owners
Michigan insurers offer a range of discounts that can meaningfully reduce what you pay for your Explorer. Discount availability and amounts vary by carrier, so comparing quotes through an independent agent often reveals savings that a single company might not offer.
Common discount categories for Michigan Explorer owners include good student discounts for teenage drivers, paid-in-full discounts, paperless billing, automatic payment, and telematics programs that track driving behavior through a smartphone app or plug-in device. Families with teen drivers often see the largest benefit from combining good student and telematics discounts.
Safety Features and Driver-Assist Technology Savings
Recent Explorer models include features such as automatic emergency braking, lane-keeping assistance, blind spot monitoring, and rear cross-traffic alerts. Some carriers offer discounts for these features because they can reduce crash frequency.
On the flip side, these same systems increase repair costs, which partially offsets the safety savings. Ask your agent which specific features your carrier credits, and provide your vehicle identification number so the insurer can accurately identify your trim's equipment.
Multi-Policy and Family Plan Incentives
Bundling your auto policy with homeowners, renters, or umbrella coverage typically produces some of the largest available discounts. Multi-vehicle discounts also apply when you insure the Explorer alongside other household vehicles.
Families should also understand how household composition affects coverage. In Frownfelter v. Esurance, decided on July 22, 2026, the Michigan Supreme Court
overruled the Grange precedent and adopted a fact-based analysis of where a child of divorced parents actually lives. If you share custody, discuss this ruling with your agent to confirm which policy will respond to your child's injuries.
Common Questions About Michigan Explorer Insurance
Is a Ford Explorer expensive to insure in Michigan? The Explorer typically costs more to insure than a small sedan because of its value and technology, but your PIP selection, driving record, and location often affect your premium more than the vehicle itself.
Do I need unlimited PIP if I have good health insurance? Not necessarily, since qualifying health coverage may allow you to select a lower PIP tier. Confirm that every household member's health plan qualifies before reducing coverage.
Does my insurance cover my boat trailer when I tow it with my Explorer? Your liability coverage generally extends to a trailer while attached, but damage to the trailer itself usually requires separate coverage. Ask your agent to verify the details in writing.
What deductible should I choose for comprehensive coverage? Many Michigan drivers choose a lower comprehensive deductible because deer strikes and windshield damage are common. Your choice should reflect the cash you can comfortably spend on a sudden repair.
Will a deer collision raise my rates? Deer collisions are typically handled under comprehensive coverage and are generally treated as not-at-fault losses, though individual carrier practices vary.
What is the best way to find affordable Explorer insurance in Michigan? Working with an independent agent who can compare several carriers is usually the most efficient way to find a tailored policy at a competitive price.
Making the Right Choice for Your Family SUV
Protecting a family SUV in Michigan requires more than selecting the lowest available quote. Your PIP tier determines how medical bills are paid for everyone in your household, your liability limits shield your savings from lawsuits, and your collision and comprehensive choices determine how quickly your Explorer returns to the road after a deer strike or winter crash.
Your path forward involves a few clear steps. Confirm whether your health coverage qualifies for a lower PIP option, review your liability limits against your assets, choose broadened collision if your Explorer is newer, and set deductibles that match your emergency savings. Then ask about every applicable discount, from bundling to safety features.
The strongest approach to Explorer insurance in Michigan comes from a careful, tailored review rather than a one-size-fits-all package. Contact a licensed Michigan insurance agent today by phone or online form to request a personalized quote, so you can drive confidently through every Michigan season knowing your family is properly protected.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying