Email us today!
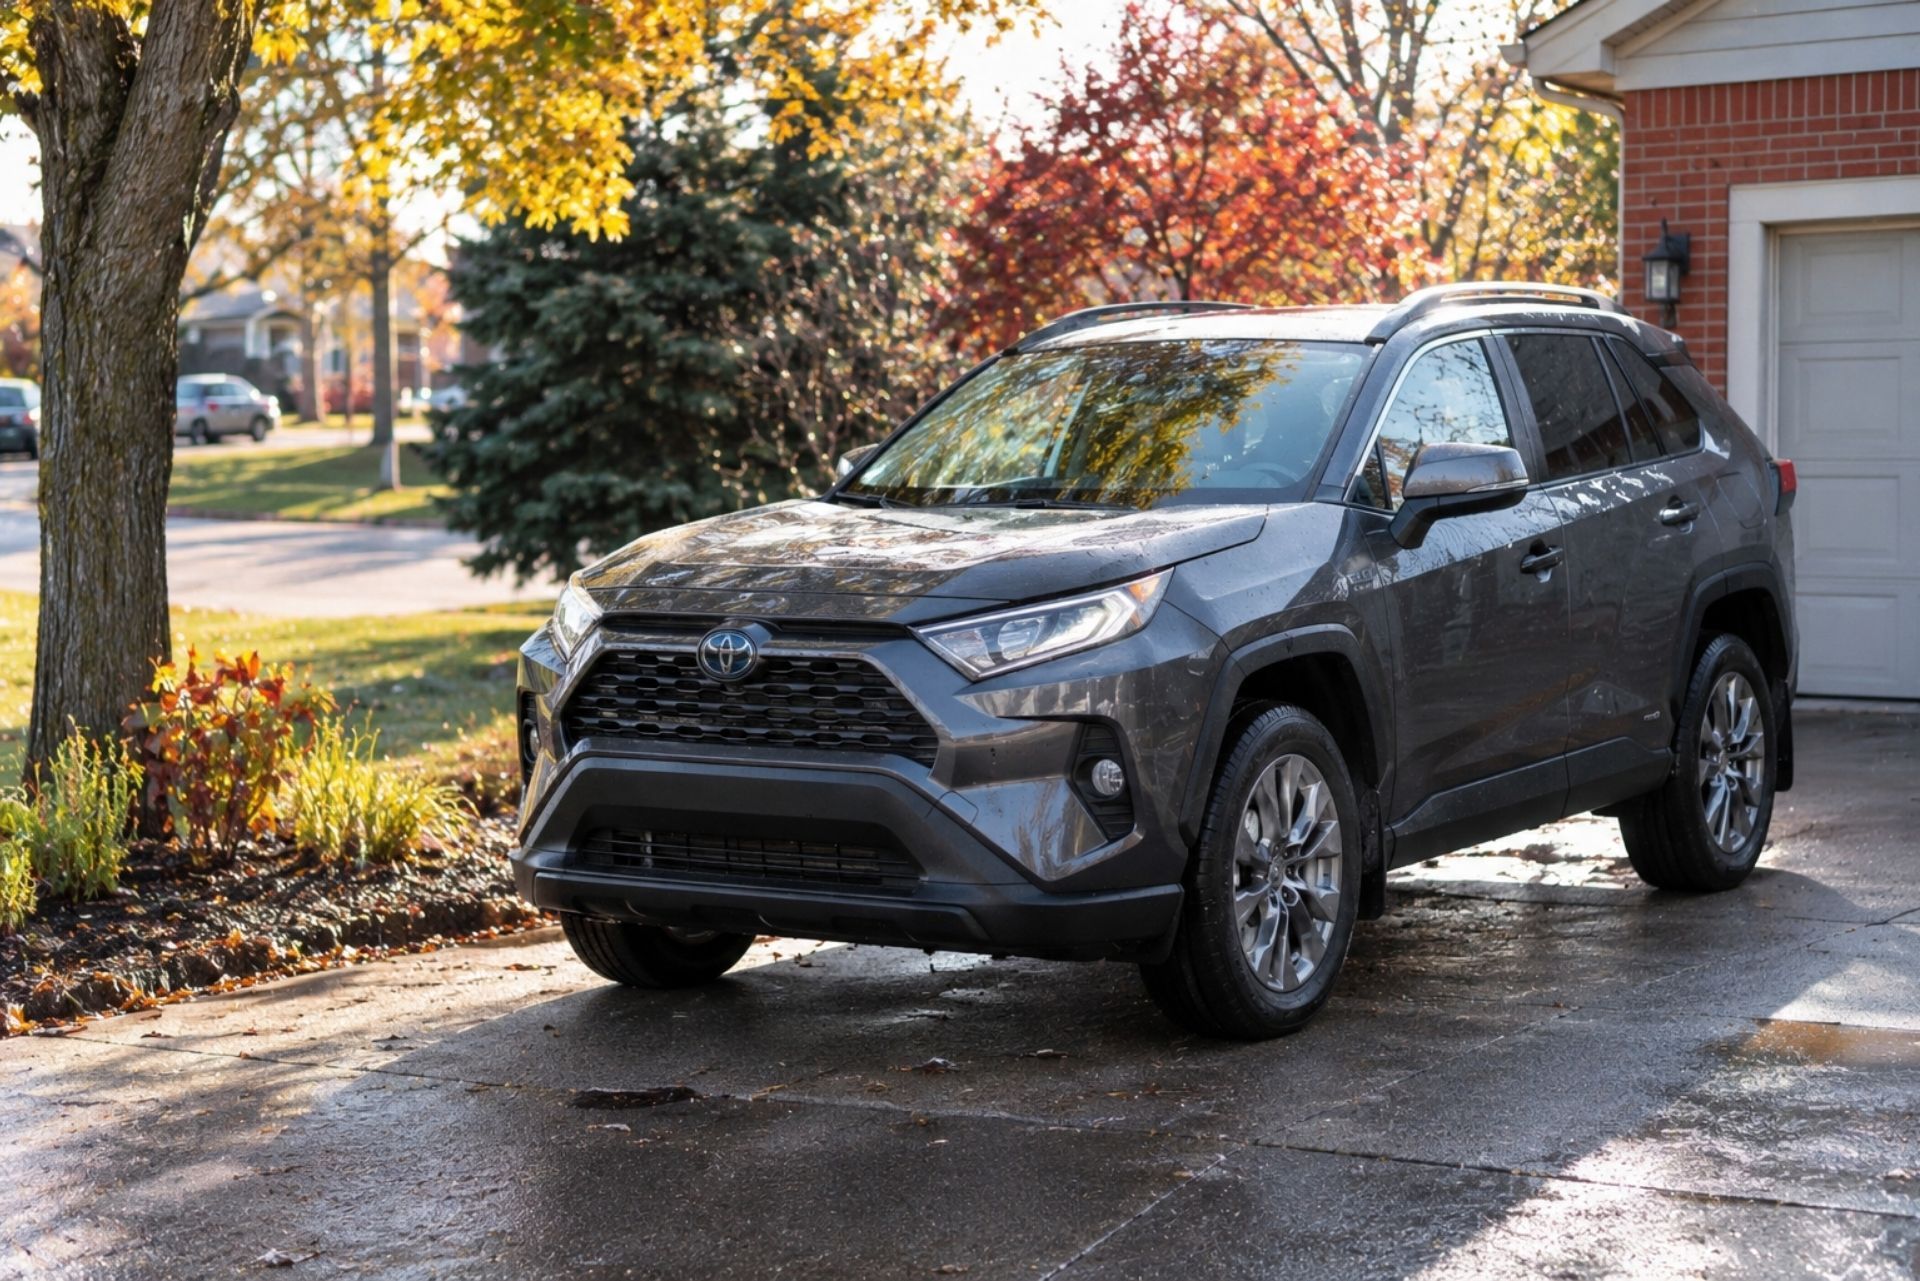
Picture a Grand Rapids family loading a RAV4 for a weekend drive up US-131, or a Troy commuter parking a hybrid trim in a Detroit garage every weekday. Each of these drivers pays premiums shaped less by the vehicle itself and more by Michigan's distinctive insurance laws. Toyota RAV4 auto insurance in Michigan follows rules that differ sharply from those in Ohio, Indiana, or any other neighboring state.
The RAV4 remains one of the most popular family SUVs on Michigan roads, and that popularity affects how insurers price it, for better and for worse. You benefit from reasonable repair costs and a strong reputation for reliability. You also face exposure to deer strikes, theft of catalytic converters and electronics, and the steep medical costs that Michigan's no-fault system was designed to absorb.
This guide covers each part of a Michigan RAV4 policy in turn: Personal Injury Protection choices, liability limits, collision options, deductibles, discounts, and the factors that drive your final premium. The goal is to help you build a tailored policy that protects your family without paying for coverage you do not need. Each section closes with a practical next step so you can apply what you learn when you request a quote.
Why Michigan Insurance Laws Impact Your Toyota RAV4 Rates
Michigan operates under a no-fault system, which means your own policy pays your medical bills after a crash, regardless of who caused it. This arrangement shifts a large portion of injury costs onto every Michigan driver's premium. As a result, a RAV4 owner in Lansing may pay more than an identical RAV4 owner across the border in Indiana, even with a spotless record.
The 2019 auto insurance reform changed that equation considerably. Before the reform, every Michigan driver had to buy unlimited lifetime medical coverage, which made the state among the most expensive in the country for auto insurance. Today, you can choose a Personal Injury Protection level that fits your health insurance and your family's needs, and that single choice often moves your premium more than any other factor.
Several other Michigan-specific elements shape your RAV4 rates:
- Property Protection Insurance (PPI): This mandatory coverage pays for damage your RAV4 causes to property such as buildings, fences, and properly parked vehicles within Michigan.
- The MCCA assessment: This per-vehicle fee funds catastrophic injury claims and varies by your PIP selection.
- Geographic rating: Insurers still price by location, so a RAV4 garaged in Detroit or Southfield often costs more to insure than one in Traverse City or Marquette.
- Michigan's unique collision options: The state offers limited, standard, and broadened collision, which no other state structures the same way.
Understanding these rules allows you to ask sharper questions when you compare quotes. The next step is to review your current declarations page and identify which of these Michigan elements your existing policy includes.
By: John G. Growney
President of Oakland Insurance
Personal Injury Protection is the core of every Michigan auto policy. PIP pays allowable medical expenses, a portion of lost wages, replacement services such as household help, and attendant care if you or your passengers sustain injuries in a crash. For a family SUV like the RAV4, which often carries children, grandparents, or carpool passengers, PIP decisions carry real weight.
The coverage follows the person, not just the vehicle. In many cases, your PIP also protects members of your household who are injured as pedestrians or while riding in another vehicle. This broad reach is one reason PIP choices deserve careful thought rather than a quick selection based on the lowest price.
Choosing the Right PIP Choice Level for Your Family
Michigan now allows several PIP levels, ranging from unlimited lifetime coverage down to lower limited options, plus a full opt-out for qualifying drivers. Selecting a lower limit reduces your premium, but it also caps what your policy will pay if a family member suffers a serious injury. Traumatic brain injuries and spinal cord injuries can generate medical and care costs that exceed lower limits within a short time.
To opt out or exclude household members, you need Qualified Health Coverage. For the 2026 to 2027 period, that coverage must not carry a deductible above the state-mandated limit of $6,579, and it must cover auto accident injuries. A common client mistake is assuming that any employer plan qualifies, only to discover later that the plan excludes auto injuries. Ask your HR department for written confirmation before you choose a reduced PIP level.
The Role of the Michigan Catastrophic Claims Association (MCCA) Fee
The MCCA reimburses insurers for catastrophic injury claims, and every Michigan policy carries an assessment to fund it. For the fiscal period from July 1, 2026, to June 30, 2027, the per-vehicle assessment is $84 for drivers with unlimited PIP, which includes a $65 pure premium and a $19 deficit recoupment charge. Drivers with other PIP limits pay only the $19 charge.
That $84 figure
represents a significant decrease from the pre-reform high of $220, making unlimited PIP more affordable than it once was. If your family owns two RAV4s, multiply the fee by each vehicle. Request a quote at more than one PIP level so you can see the actual price difference for your household.
Liability and Property Protection Requirements for SUVs
Residual Bodily Injury and Property Damage liability, often shortened to BI/PD, protects you when you cause a serious accident and face a lawsuit. Michigan's no-fault system does not eliminate lawsuits. Injured parties can still sue for pain and suffering if they meet the state's injury threshold, and they can pursue excess medical costs if their own PIP limit runs out.
That second point matters more than many RAV4 owners realize. Because other drivers may now carry lower PIP limits, an at-fault driver can be sued for medical bills that exceed the injured person's coverage. The 2019 reform raised Michigan's default liability limits for this reason, and drivers who choose lower limits must sign a specific form to do so.
For a family SUV, the following liability components deserve attention:
- Bodily injury liability: Covers injuries you cause to others, including legal defense costs. Families with homes, savings, or retirement accounts should consider limits well above the state minimum.
- Property Protection Insurance: Pays for damage your RAV4 causes to property in Michigan, such as a storefront, mailbox, or parked car.
- Residual property damage: Covers damage you cause outside Michigan, which matters on trips to Ohio, Indiana, or Ontario.
- Limited Property Damage (mini-tort): Allows you to recover a capped amount from an at-fault driver for vehicle damage, often used to offset a deductible.
An umbrella policy can extend liability protection beyond your auto limits, and it is often inexpensive relative to the protection it provides. Ask your agent whether your current limits match your assets, and request an umbrella quote alongside your RAV4 policy.
Protecting Your RAV4: Collision and Comprehensive Coverage
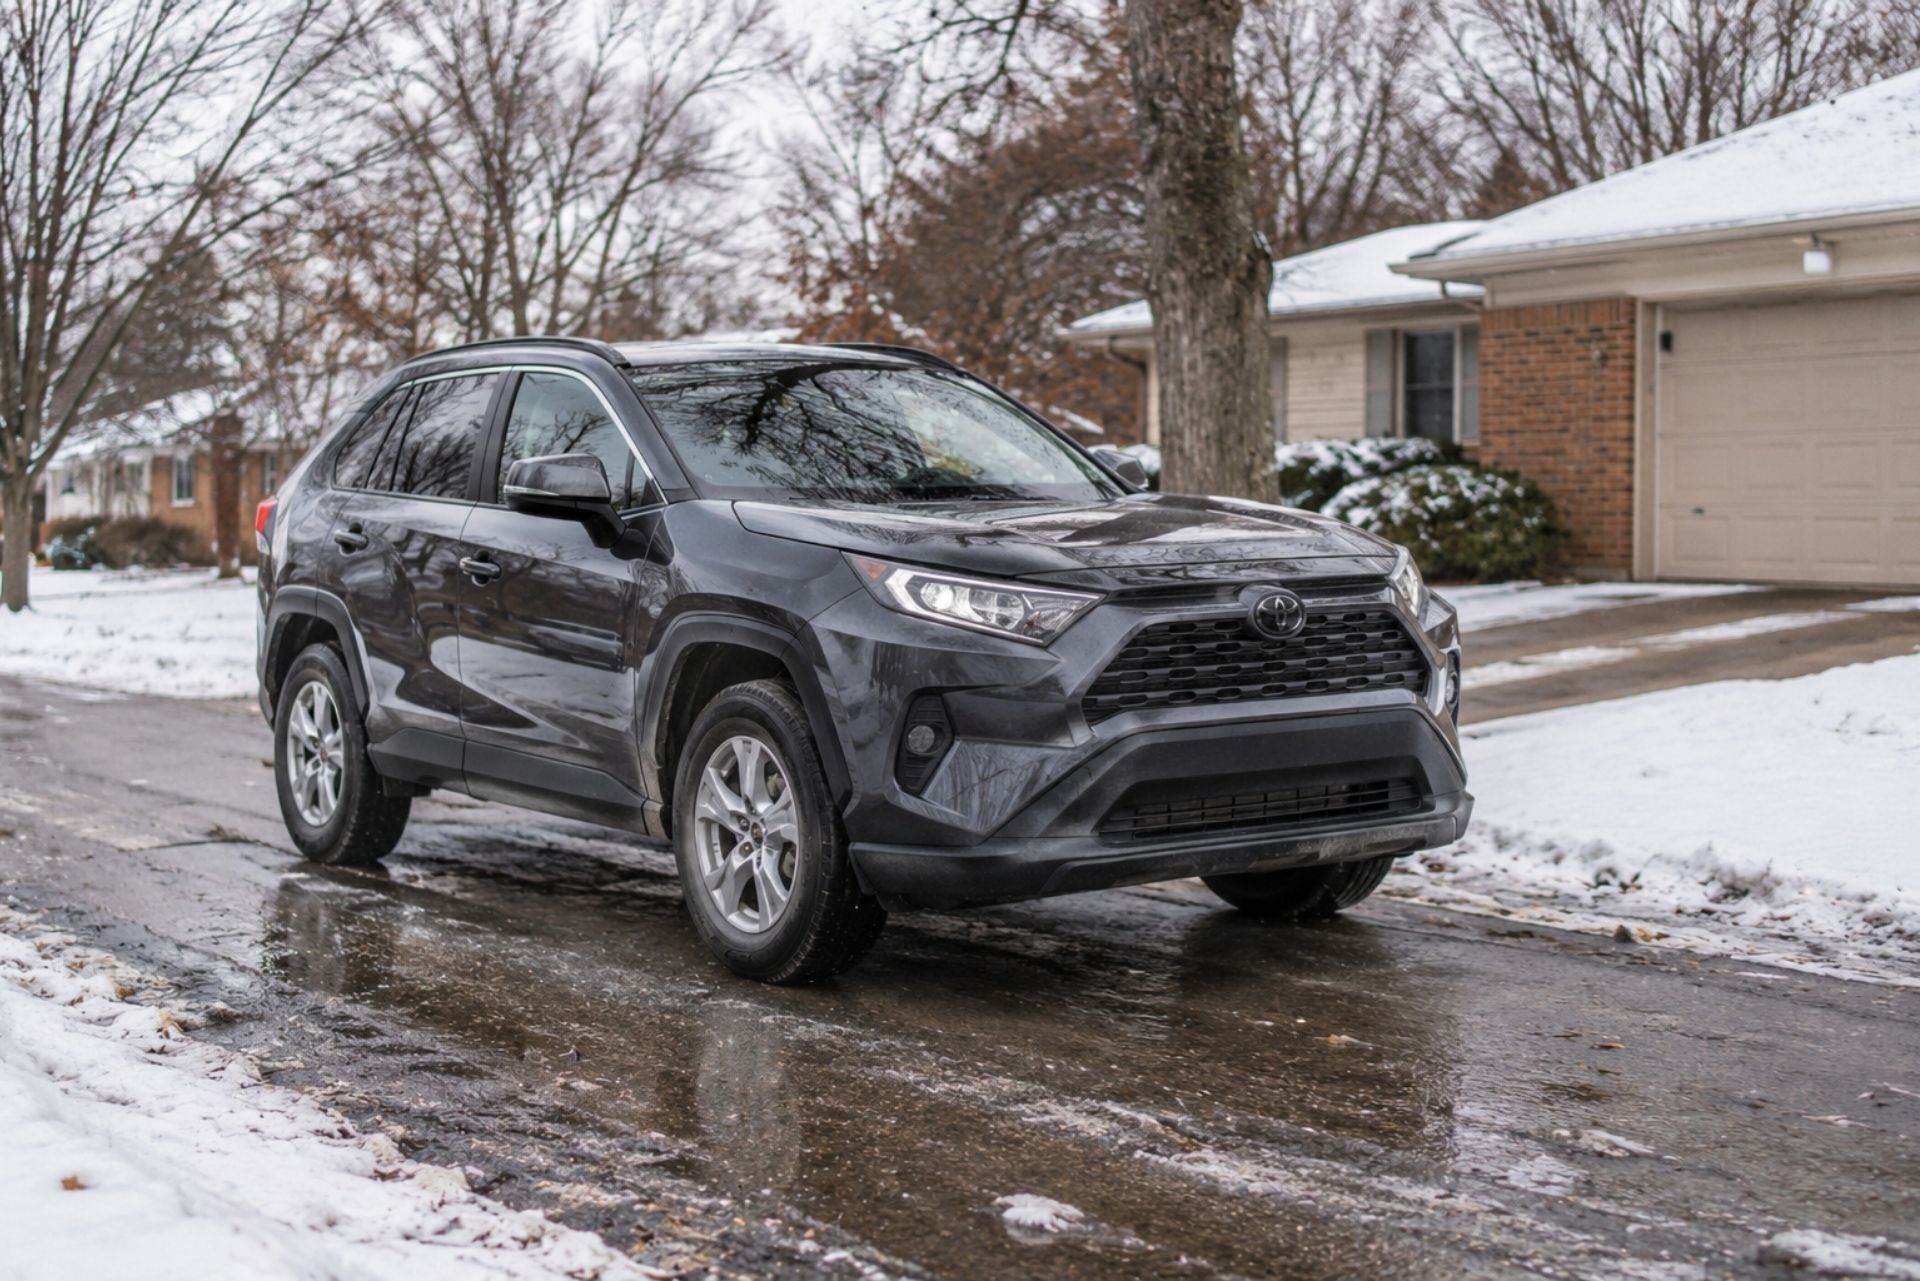
Physical damage coverage repairs or replaces your RAV4 itself. Because Michigan no-fault largely prevents you from suing another driver for vehicle damage beyond the mini-tort amount, your own collision coverage carries more importance in Michigan than in traditional fault states. Without it, you may absorb most of the repair bill even when another driver causes the crash.
If you lease or finance your RAV4, your lender will almost certainly require both collision and comprehensive coverage. Many owners also add gap insurance, which pays the difference between your loan balance and the vehicle's actual cash value after a total loss.
Standard vs. Broadened Collision in Michigan
Michigan insurers typically offer three collision options. Limited collision pays only when you are not substantially at fault, and it pays nothing when you are. Standard collision pays regardless of fault, minus your deductible. Broadened collision also pays regardless of fault, but it waives your deductible when you are not substantially at fault.
For most families driving a newer RAV4, broadened collision offers the strongest value. Consider a common claim: another driver rear-ends your RAV4 at a Novi intersection, causing several thousand dollars in damage. With broadened collision, you pay no deductible. With standard collision, you pay the full deductible and may try to recover part of it through mini-tort.
Comprehensive Coverage for Theft and Deer Strikes
Comprehensive covers non-collision losses such as theft, vandalism, fire, falling trees, hail, flooding, and animal strikes. Michigan consistently reports high numbers of deer-vehicle crashes, especially during fall rutting season in October and November. A deer strike on a rural road near Clarkston or Gaylord falls under comprehensive, not collision, which surprises many drivers.
Hybrid RAV4 models also face catalytic converter theft risk, and comprehensive covers that loss. Confirm that your comprehensive deductible is one you can comfortably afford during deer season.
The gap between a minimum Michigan policy and a full protection policy can look small on paper, yet it becomes enormous after a claim. Many families choose the cheaper option without seeing how much financial risk they retain. The comparison below shows where the differences appear.
| Coverage Element | Basic Michigan Policy | Full Protection Policy |
|---|---|---|
| PIP | Lower limited option or opt-out | Unlimited or higher limited option |
| Liability (BI/PD) | Reduced limits with signed form | Default or higher limits, plus umbrella |
| PPI | Required, included | Required, included |
| Collision | None or limited | Broadened collision |
| Comprehensive | None | Included, moderate deductible |
| Deer strike repair | You pay | Covered after deductible |
| Lender approval | Not acceptable for loans | Meets lender requirements |
| Rental and towing | Not included | Often included |
A basic policy may suit an older, paid-off RAV4 with low market value, driven by someone with strong health insurance and modest assets. Full protection generally makes sense for newer models, financed vehicles, and households with children or significant savings.
The practical middle ground often involves keeping higher PIP and liability limits while adjusting physical damage coverage as your RAV4 ages. Ask for quotes on both configurations so you can weigh the actual price difference against the protection you would give up.
Managing Your Deductible and Out-of-Pocket Costs
Your deductible is the amount you pay before collision or comprehensive coverage begins paying. Raising it lowers your premium, while lowering it increases your premium. The right choice depends on your emergency savings, not simply on which number produces the cheapest quote.
A useful guideline is to set your deductible at an amount you could pay tomorrow without borrowing. If a deer strike in November forces you to choose between a repair and a mortgage payment, your deductible is too high. On the other hand, paying for a very low deductible can cost more over several years than the occasional claim it would save you.
Consider these Michigan-specific strategies for managing out-of-pocket costs:
- Split your deductibles. Many insurers allow different collision and comprehensive deductibles, so you can keep comprehensive lower for deer season while raising collision.
- Pair broadened collision with a higher deductible. Because broadened collision waives the deductible when you are not at fault, a higher deductible mainly affects at-fault claims.
- Understand the mini-tort process. When another driver causes damage, you can pursue limited recovery to offset part of your deductible.
- Watch PIP coordination. If you coordinate PIP with health insurance, your health plan deductible and copays may apply to injury claims.
Review your deductibles at every renewal, particularly after you pay off a loan or build your savings. Your agent can show you the premium difference between deductible levels in a single quote.
Maximizing Toyota RAV4 Safety Features for Insurance Discounts
The RAV4's safety equipment can reduce your premium, though insurers weigh crash test data and claims history carefully. Recent results add nuance. The 2026 RAV4 earned an "Acceptable" rating in the IIHS updated moderate overlap front crash test and did not receive a 2026 Top Safety Pick award because of rear seatbelt concerns.
The RAV4 was also among several small SUVs that did not receive the highest rating in tougher back-seat crash testing. For families who seat children or older relatives in the second row, this information supports carrying strong PIP coverage rather than reducing it.
Toyota Safety Sense and Anti-Theft Savings
Toyota Safety Sense, standard on recent RAV4 models, includes features such as pre-collision braking, lane departure alerts, and adaptive cruise control. Some insurers credit these features directly, while others reflect them through lower claims data for the model. Ask specifically whether your insurer offers an advanced driver assistance discount.
Anti-theft discounts may apply for factory immobilizers, alarm systems, and tracking services. Catalytic converter etching or shields on hybrid trims may also help reduce theft risk, even when no formal discount exists.
Multi-Policy and Good Driver Incentives
Bundling your RAV4 policy with homeowners or renters insurance often produces some of the largest savings available. Michigan carriers also commonly offer discounts for clean driving records, paid-in-full premiums, paperless billing, good student status, and telematics programs that track safe driving.
Telematics programs suit careful drivers well, but they can work against you if your daily commute involves frequent hard braking on I-696 or I-94. Request a discount review with your agent to confirm every credit you qualify for.
Average Insurance Costs by RAV4 Model Year and Trim
Insurers price each RAV4 based on several variables, and premiums for the same model can vary widely between two Michigan households. Rather than relying on a single statewide average, you will get a more accurate picture by understanding how each factor moves your rate.
Model year affects cost in two directions. A newer RAV4 carries a higher actual cash value, which increases the cost of collision and comprehensive coverage. An older RAV4 costs less to cover for physical damage, yet it may lack the safety features that earn discounts. Liability and PIP costs, by contrast, depend mostly on the driver and location rather than the vehicle's age.
Trim level matters as well. Hybrid and plug-in hybrid models include battery systems and electronics that can raise repair costs after a collision. Higher trims with larger wheels, advanced sensors, and premium lighting may also cost more to repair, since even a minor front-end collision can require sensor recalibration. Base trims typically carry the lowest physical damage premiums.
Your final premium also reflects factors unrelated to the vehicle:
- Your ZIP code, with metro Detroit areas generally priced higher than northern Michigan
- Your PIP choice and liability limits
- Your driving record and claims history
- Household drivers, especially teenagers
- Annual mileage and commute distance
The most reliable approach is to request quotes for the specific RAV4 year and trim you own or plan to buy. If you are shopping for a RAV4, get an insurance quote before you sign the purchase agreement.
Common Questions About Insuring a RAV4 in Michigan
- Is a RAV4 expensive to insure in Michigan? Usually not compared with larger SUVs, since repair costs are moderate. Your PIP level and ZIP code typically affect your premium far more than the vehicle itself.
- Do I need full coverage on a financed RAV4? Yes, lenders and lessors almost always require collision and comprehensive coverage. Many also recommend gap insurance for newer vehicles.
- Does my insurance cover hitting a deer? Comprehensive coverage pays for deer strikes after your deductible. Collision coverage does not, so drivers without comprehensive pay these repairs themselves.
- Can I opt out of PIP if I have health insurance? Only if your plan counts as Qualified Health Coverage and meets the deductible limit, which is $6,579 for the 2026 to 2027 period. Medicare enrollees have separate rules, so confirm eligibility with your agent.
- Will a hybrid RAV4 cost more to insure? It can, because battery components and electronics raise repair costs. Safety discounts and lower theft risk with proper precautions may offset part of that difference.
- What happens if someone else hits my RAV4?
Your broadened collision coverage pays without a deductible if you are not substantially at fault. Without collision coverage, you are limited mainly to mini-tort recovery.
Making the Right Choice for Your Family's Safety
A sound Michigan RAV4 policy rests on a few deliberate decisions: a PIP level that matches your health coverage and household, liability limits that protect your savings, broadened collision for newer vehicles, and comprehensive coverage that prepares you for deer season. Discounts and deductibles then fine-tune the cost.
Your path forward can follow a simple order:
- Confirm whether your health plan qualifies for reduced PIP.
- Compare liability limits against your assets.
- Choose collision and comprehensive based on your RAV4's value and loan status.
- Set deductibles you can pay without strain.
- Request a full discount review.
Families who revisit these choices each renewal often find savings while keeping protection intact. Contact a licensed Michigan insurance professional today to request a tailored RAV4 quote, and compare at least two PIP levels side by side before you decide. The right policy is the one that still protects your family on the worst day, not merely the one with the lowest price.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying