Email us today!
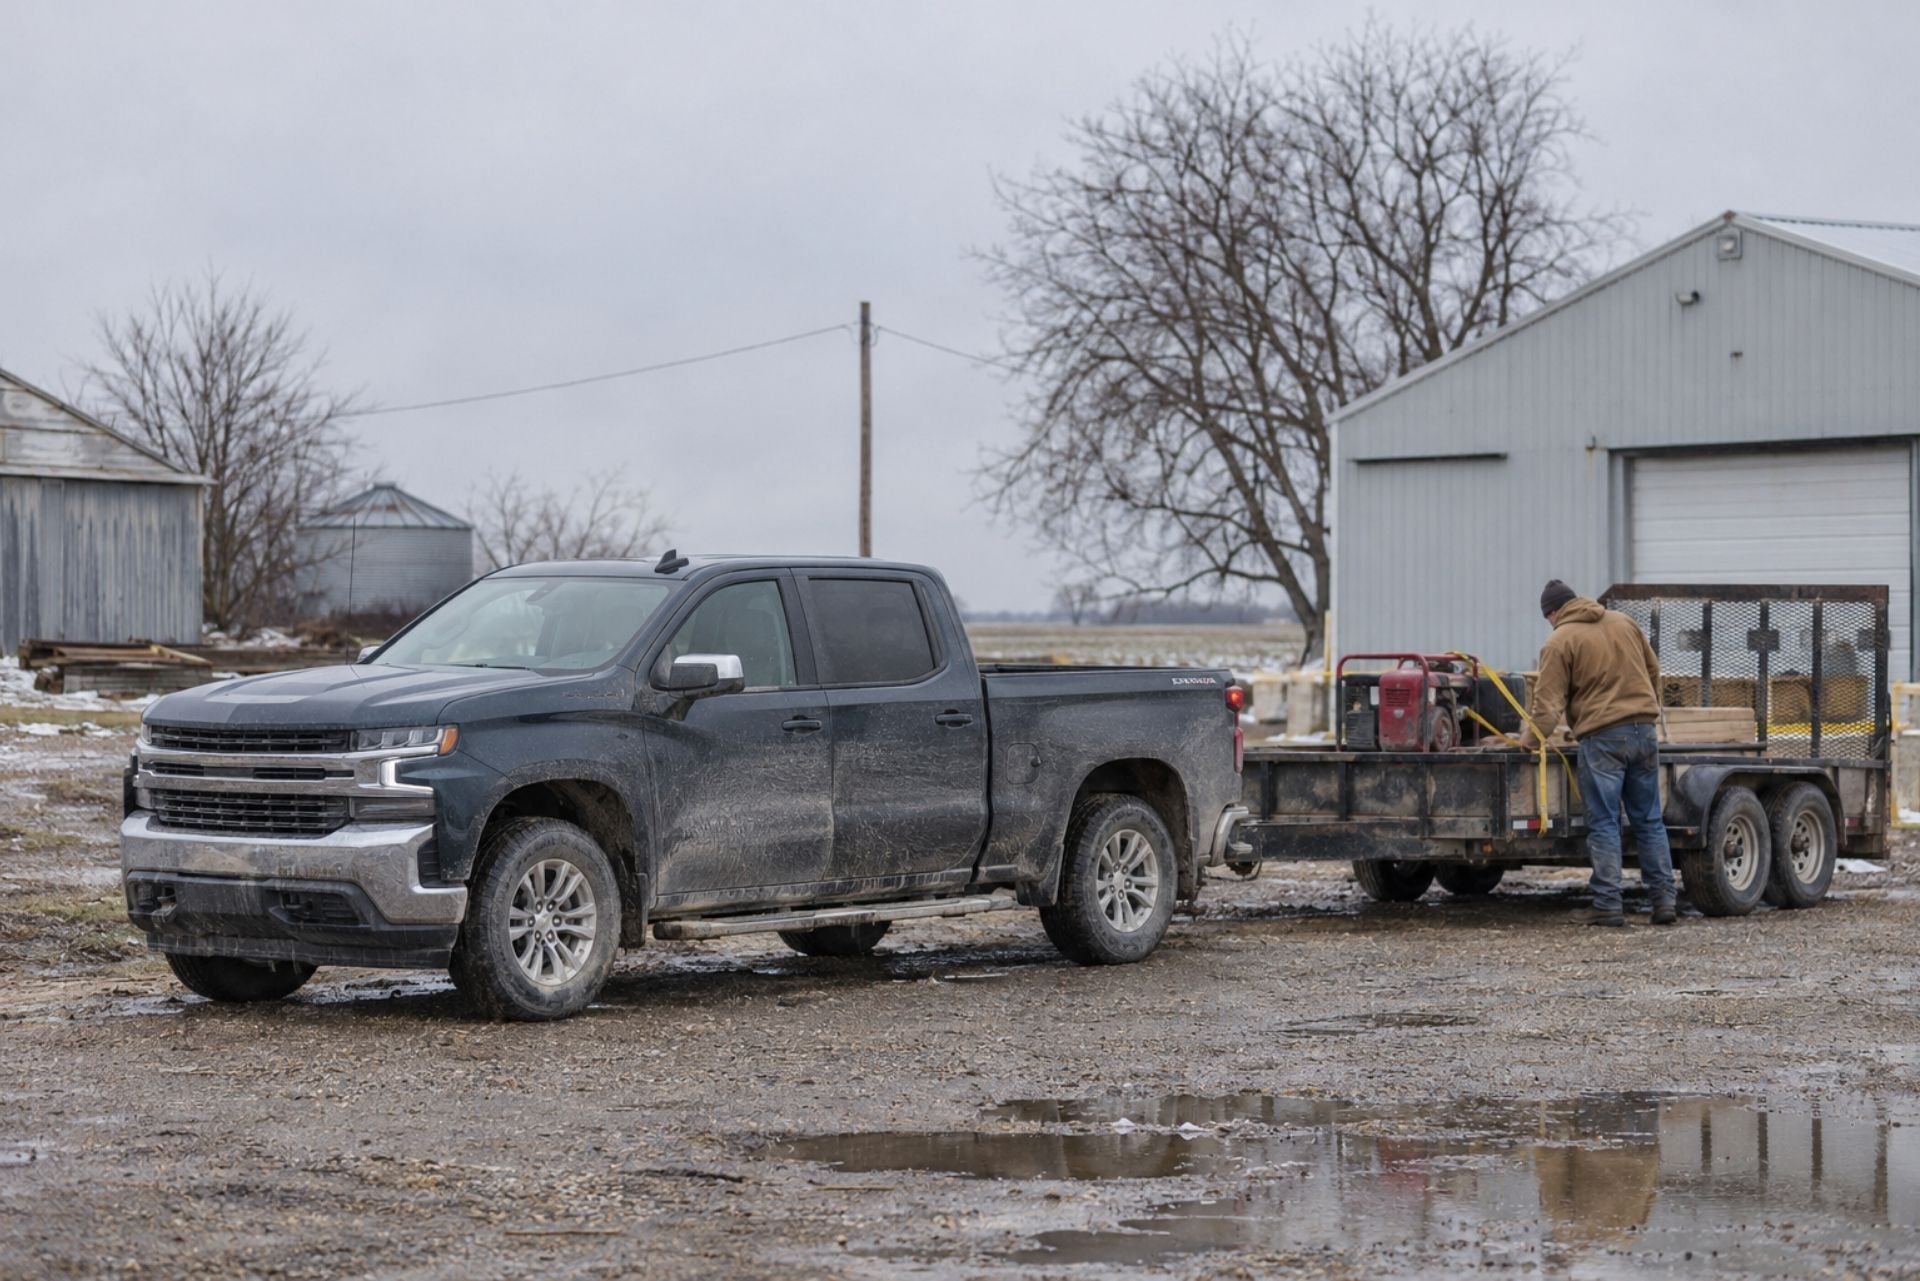
Picture a Silverado 2500HD hauling a loaded equipment trailer down I-96 on a February morning, when a patch of black ice sends the rig sliding into a guardrail outside Novi. In that moment, the details of your Chevrolet Silverado insurance in Michigan determine whether the repair, the tow, the trailer, and any injuries become manageable claims or serious out-of-pocket losses. For contractors and tradespeople who depend on their trucks every day, that difference can decide whether a business keeps operating or stalls for weeks.
Michigan's auto insurance system works differently from the systems in nearly every other state, and a full-size pickup adds layers of complexity that a sedan never introduces. Your Silverado may carry a lift kit, a tonneau cover, a plow mount, a toolbox full of equipment, or a fifth-wheel hitch, and each of those features changes how a claim unfolds. Choices you make about personal injury protection, liability limits, and collision coverage carry real financial consequences in a state where premiums remain among the highest in the nation.
This guide explains each coverage decision in plain, formal terms so that you can build a policy that matches the way you actually use your truck.
Insuring Your Chevrolet Silverado in Michigan
The Chevrolet Silverado is one of the most popular trucks on Michigan roads, and insurers price it with a clear understanding of its strengths and its risks. A Silverado 1500 used for commuting in Ann Arbor presents a different risk profile than a Silverado 3500HD pulling a dump trailer between job sites in Clarkston. Insurers weigh repair costs, theft rates, vehicle weight, and the potential for damage to other vehicles when they calculate your premium.
Cost is the first concern for most Silverado owners, and the concern is justified. Michigan remains the most expensive state for auto insurance in 2026, with premiums consuming a median of 3.28% of household income. For a business owner insuring one or more pickups, that burden compounds quickly.
There is some encouraging movement in the market. In 2026, State Farm implemented a 4.9% rate cut for Michigan drivers, while Progressive reduced rates by 2.8%. These reductions show that shopping your policy at renewal can produce real savings, particularly if your current carrier has not adjusted its pricing.
One distinction matters before you compare any quotes. If your Silverado is titled to your business, used primarily for hauling tools and materials, or driven by employees, you likely need a commercial auto policy rather than a personal one. A common and costly mistake occurs when a contractor insures a work truck on a personal policy, then discovers after an accident that the carrier excludes business use. Discussing your actual driving patterns with a licensed Michigan agent ensures that your coverage is tailored to how the Silverado really operates.
By: John G. Growney
President of Oakland Insurance
Michigan's no-fault system means that your own insurer pays your medical expenses and certain other losses after an accident, regardless of who caused the crash. This structure is designed to deliver medical benefits quickly without waiting for a fault determination or a lawsuit. Personal injury protection, commonly called PIP, is the core of that system, and it is mandatory on every Michigan auto policy.
PIP generally covers medical treatment, a portion of lost wages, replacement services such as household help you can no longer perform, and certain attendant care. For a tradesperson whose income depends on physical work, the wage loss benefit can be just as valuable as the medical benefit. A roofer with a back injury may be unable to work for months, and PIP helps bridge that gap.
Choosing Your PIP Medical Limit
Since the 2019 reform took effect, Michigan drivers have been required to select from six PIP medical tiers, ranging from unlimited coverage with no dollar cap on benefits down to a $50,000 limit restricted to Medicaid enrollees. Intermediate options set specific dollar caps, and qualifying Medicare recipients may opt out of PIP medical coverage entirely. Lower limits reduce your premium, but they also shift the risk of catastrophic medical bills onto you and your health insurance.
Fee schedules also affect how far your PIP dollars stretch. Effective July 2, 2026, the Michigan Department of Insurance and Financial Services applied a 16.38% CPI-based increase to the medical provider fee schedule, which raises the maximum amounts insurers pay for covered medical services. Higher payments to providers mean a capped PIP limit may be exhausted sooner in a serious injury claim.
Before choosing a lower tier, confirm that your health plan does not exclude auto accident injuries. Many self-employed contractors carry high-deductible or limited plans, and those plans may leave large gaps after a severe crash.
Residual Liability and Property Protection
Residual bodily injury liability protects you if you seriously injure someone and they sue you beyond what no-fault covers. The default limits under current Michigan law are higher than the minimum you may select, and lowering them requires a signed form. For a heavy pickup capable of causing severe injuries, keeping higher limits is the prudent choice, particularly if your business assets are exposed.
Property protection insurance, or PPI, pays for damage your Silverado causes to other people's property within Michigan, such as buildings, fences, and properly parked vehicles. Damage to another moving vehicle is handled differently, which is where the mini-tort provision applies. The Michigan mini-tort limit remains at $3,000 for 2026, allowing drivers to recover vehicle damage costs not covered by their own insurance from an at-fault party. If you cause an accident, your liability coverage can pay that mini-tort claim on your behalf, provided you carry the optional mini-tort endorsement.
Protecting Your Silverado: Collision and Comprehensive
A late-model Silverado represents a significant investment, and Michigan's no-fault system does not automatically pay to repair your own truck after a crash. Collision and comprehensive coverage fill that role. If you finance or lease your Silverado, your lender will almost certainly require both.
Standard vs. Broadened Collision Coverage
Michigan insurers typically offer several forms of collision coverage, and the differences matter more than most drivers realize. Limited collision pays only when you are not substantially at fault, and it usually carries no deductible in those cases. Standard collision pays for damage to your truck regardless of fault, but you pay your deductible every time.
Broadened collision combines elements of both. Under broadened collision, you pay your deductible only when you are substantially at fault, and the deductible is waived when another driver is more responsible for the crash. For a Silverado that spends long hours on congested routes through Detroit, Grand Rapids, or Lansing, broadened collision often delivers the best balance of cost and protection.
Consider a practical example. Another driver backs into your parked Silverado at a supply yard, causing $4,500 in damage. With broadened collision, your insurer pays the repair without charging your deductible, whereas standard collision would require you to pay the deductible and then pursue a mini-tort recovery, capped at $3,000, from the other driver.
Comprehensive Coverage for Theft and Nature
Comprehensive coverage pays for damage that does not result from a collision with another vehicle. In Michigan, the most common comprehensive claims for pickups include:
- Deer strikes: Michigan's rural highways and suburban edges produce frequent animal collisions, especially in fall
- Hail and storms: Spring and summer storms can dent hoods, roofs, and bed rails
- Falling objects: Tree limbs during ice storms damage windshields and cab roofs
- Theft and vandalism: Full-size pickups and their tailgates, catalytic converters, and wheels attract thieves
- Glass damage: Gravel from construction zones and plow trucks cracks windshields regularly
A deer strike surprises many new Michigan drivers because it falls under comprehensive rather than collision. If you drop comprehensive to save money, you lose protection against one of the most likely claims a Silverado owner will ever file
Coverage Comparison: Basic vs. Full Protection
The right level of coverage depends on your truck's value, how you use it, and how much financial risk you can absorb. The following comparison shows how a minimal policy differs from a fully protected one for a working Silverado.
| Coverage Area | Basic Protection | Full Protection |
|---|---|---|
| PIP Medical | Lower capped tier | Unlimited or high tier |
| Residual Liability | Reduced limits by signed form | Default or higher limits |
| Property Protection (PPI) | Required, included | Required, included |
| Mini-Tort | Often excluded | Included up to $3,000 |
| Collision | None or limited | Broadened collision |
| Comprehensive | None | Included, moderate deductible |
| Custom Equipment | Not covered | Endorsement for parts and accessories |
| Towing and Labor | Not included | Included with heavy-duty limits |
| Best Suited For | Older, paid-off trucks | Financed, newer, or work trucks |
Basic protection can make sense for an older Silverado with low market value that you could replace without strain. Paying for collision on a truck worth very little often costs more over a few years than the truck itself.
Full protection fits nearly every contractor who relies on a Silverado to earn income. When the truck is down, your crew is down, and the cost of lost jobs can far exceed the premium difference. A tailored policy built around your truck's actual role is almost always more economical than learning about a coverage gap after a claim.
Custom Equipment and Roadside Assistance
Silverado owners modify their trucks more than almost any other group of drivers. Lift kits, upgraded wheels, light bars, bed liners, ladder racks, and plow setups are common across Michigan, particularly among tradespeople and rural owners. Standard policies, however, are written around the truck as it left the factory.
Insuring Aftermarket Parts and Lift Kits
Most auto policies cover only a small amount of custom parts and equipment unless you add a specific endorsement. If your Silverado carries a several-thousand-dollar lift kit and premium wheels, a total loss claim may pay only the value of a stock truck. This is one of the most frequent disputes adjusters encounter with modified pickups.
To protect your investment, follow these steps:
- Keep receipts and installation invoices for every aftermarket part
- Photograph the truck and its modifications from multiple angles each year
- Ask your agent to add a custom parts and equipment endorsement with an adequate limit
- Report new modifications promptly rather than waiting until renewal
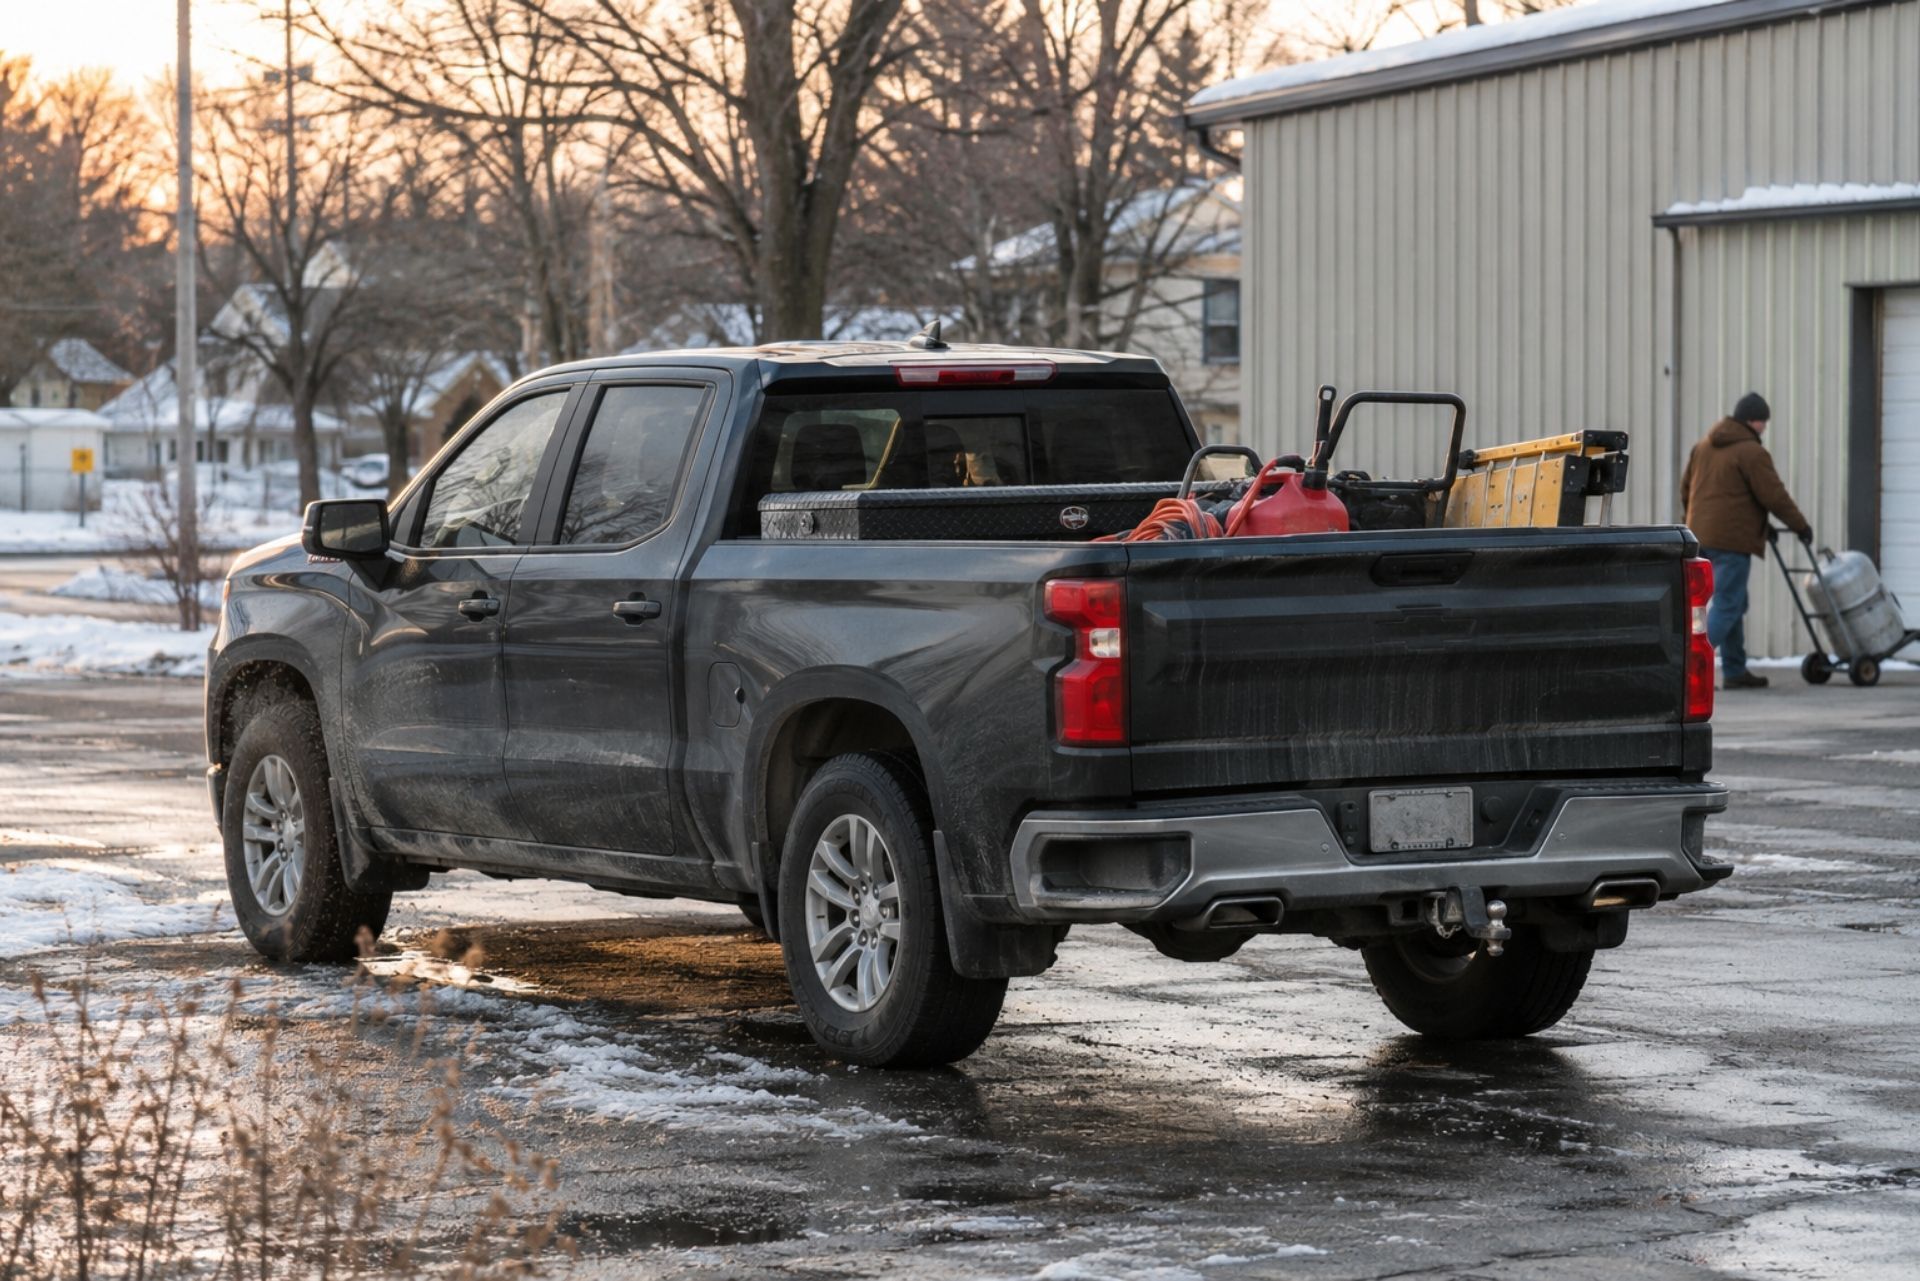
One thing to keep in mind is that tools and materials stored in your truck are generally not covered by auto insurance at all. A contractor's toolbox stolen from a Silverado bed in Royal Oak would typically fall under an inland marine or tools and equipment policy. Pairing your auto coverage with that business policy closes a gap many tradespeople overlook.
Towing and Labor for Heavy Duty Trucks
Towing a Silverado 2500HD or 3500HD requires heavier equipment than towing a passenger car, and the bill reflects that. Some basic roadside plans cap reimbursement at levels that barely cover a light-duty tow, leaving you to pay the balance for a heavy-duty wrecker.
When reviewing towing and labor coverage, confirm the per-occurrence limit, whether the plan covers heavy-duty trucks, and whether attached trailers are included. A breakdown on US-131 north of Cadillac in January can leave you stranded with a loaded trailer, and the cost of moving both the truck and trailer can surprise you. Rental reimbursement coverage deserves equal attention, since finding a comparable pickup during repairs is rarely inexpensive.
Your deductible is the amount you pay before collision or comprehensive coverage begins. Raising your deductible lowers your premium, but it also increases what you must pay when a claim occurs. The goal is to choose a deductible you could comfortably cover tomorrow without disrupting your business.
Many Silverado owners choose different deductibles for collision and comprehensive. A lower comprehensive deductible makes sense in Michigan because deer strikes, hail, and glass claims are common and often unavoidable. A higher collision deductible can reduce costs if you have a clean driving record and confidence in your experience behind the wheel.
Beyond deductibles, several strategies can reduce your premium:
- Bundle policies: Combining auto with home, business, or umbrella coverage often earns a multi-policy discount
- Review PIP selection carefully: Choosing a lower tier reduces cost, but only after confirming your health coverage
- Install anti-theft devices: GPS tracking and immobilizers can lower comprehensive rates
- Maintain a clean record: Tickets and at-fault claims raise rates for years
- Shop at renewal: Recent rate cuts by major carriers show that pricing shifts year to year
- Use telematics programs: Safe-driving apps can produce discounts for careful drivers
Rates are stabilizing across the industry, yet service quality still varies. A 2026 industry study found that the market has
shifted from a pricing crisis to an experience challenge, with many customers frustrated when they must switch channels to resolve a single inquiry. Choosing an agent who handles your claims and questions directly can save you hours when your truck is out of service.
Common Questions About Silverado Insurance
Does Michigan no-fault cover damage to my Silverado? No. No-fault PIP covers medical costs and related losses, while repairs to your own truck require collision or comprehensive coverage.
Is a deer hit covered by collision or comprehensive? Hitting a deer is covered under comprehensive. Swerving to avoid a deer and hitting a tree is usually treated as a collision claim.
Do I need commercial insurance if I use my Silverado for work? If the truck is owned by your business, carries signage, or is regularly used to haul tools and materials, you likely need a commercial auto policy. Ask your agent to review your use before a claim forces the question.
Will my lift kit be covered after an accident? Only up to a small limit unless you add a custom equipment endorsement. Keep receipts so the full value can be documented.
What PIP level should I choose? The right tier depends on your health insurance, income, and assets. Unlimited PIP offers the broadest protection, while lower tiers save money but transfer risk to you.
Does my policy cover a trailer I tow with my Silverado? Liability generally extends to a trailer you are towing, but physical damage to the trailer itself often requires separate coverage. Confirm this before hauling expensive equipment.
Making the Right Choice for Your Truck
The best Silverado coverage in Michigan reflects how you really use your truck, not just the minimum the law requires. Start by confirming whether your Silverado belongs on a personal or commercial policy, then choose a PIP tier that matches your health coverage and income needs. Keep residual liability limits high, select broadened collision for daily-driven trucks, and protect any lift kits, racks, or accessories with a custom equipment endorsement.
Your path forward is straightforward. Gather your vehicle details, modification receipts, and current declarations page, then compare quotes at renewal while recent rate cuts are still reshaping the market. A tailored policy built by a Michigan agent who understands pickups and the trades can close the gaps that cost owners the most.
Contact a licensed Michigan insurance professional today, call or complete an online quote request, and make sure your Silverado is protected before the next icy morning on the highway.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying