Email us today!
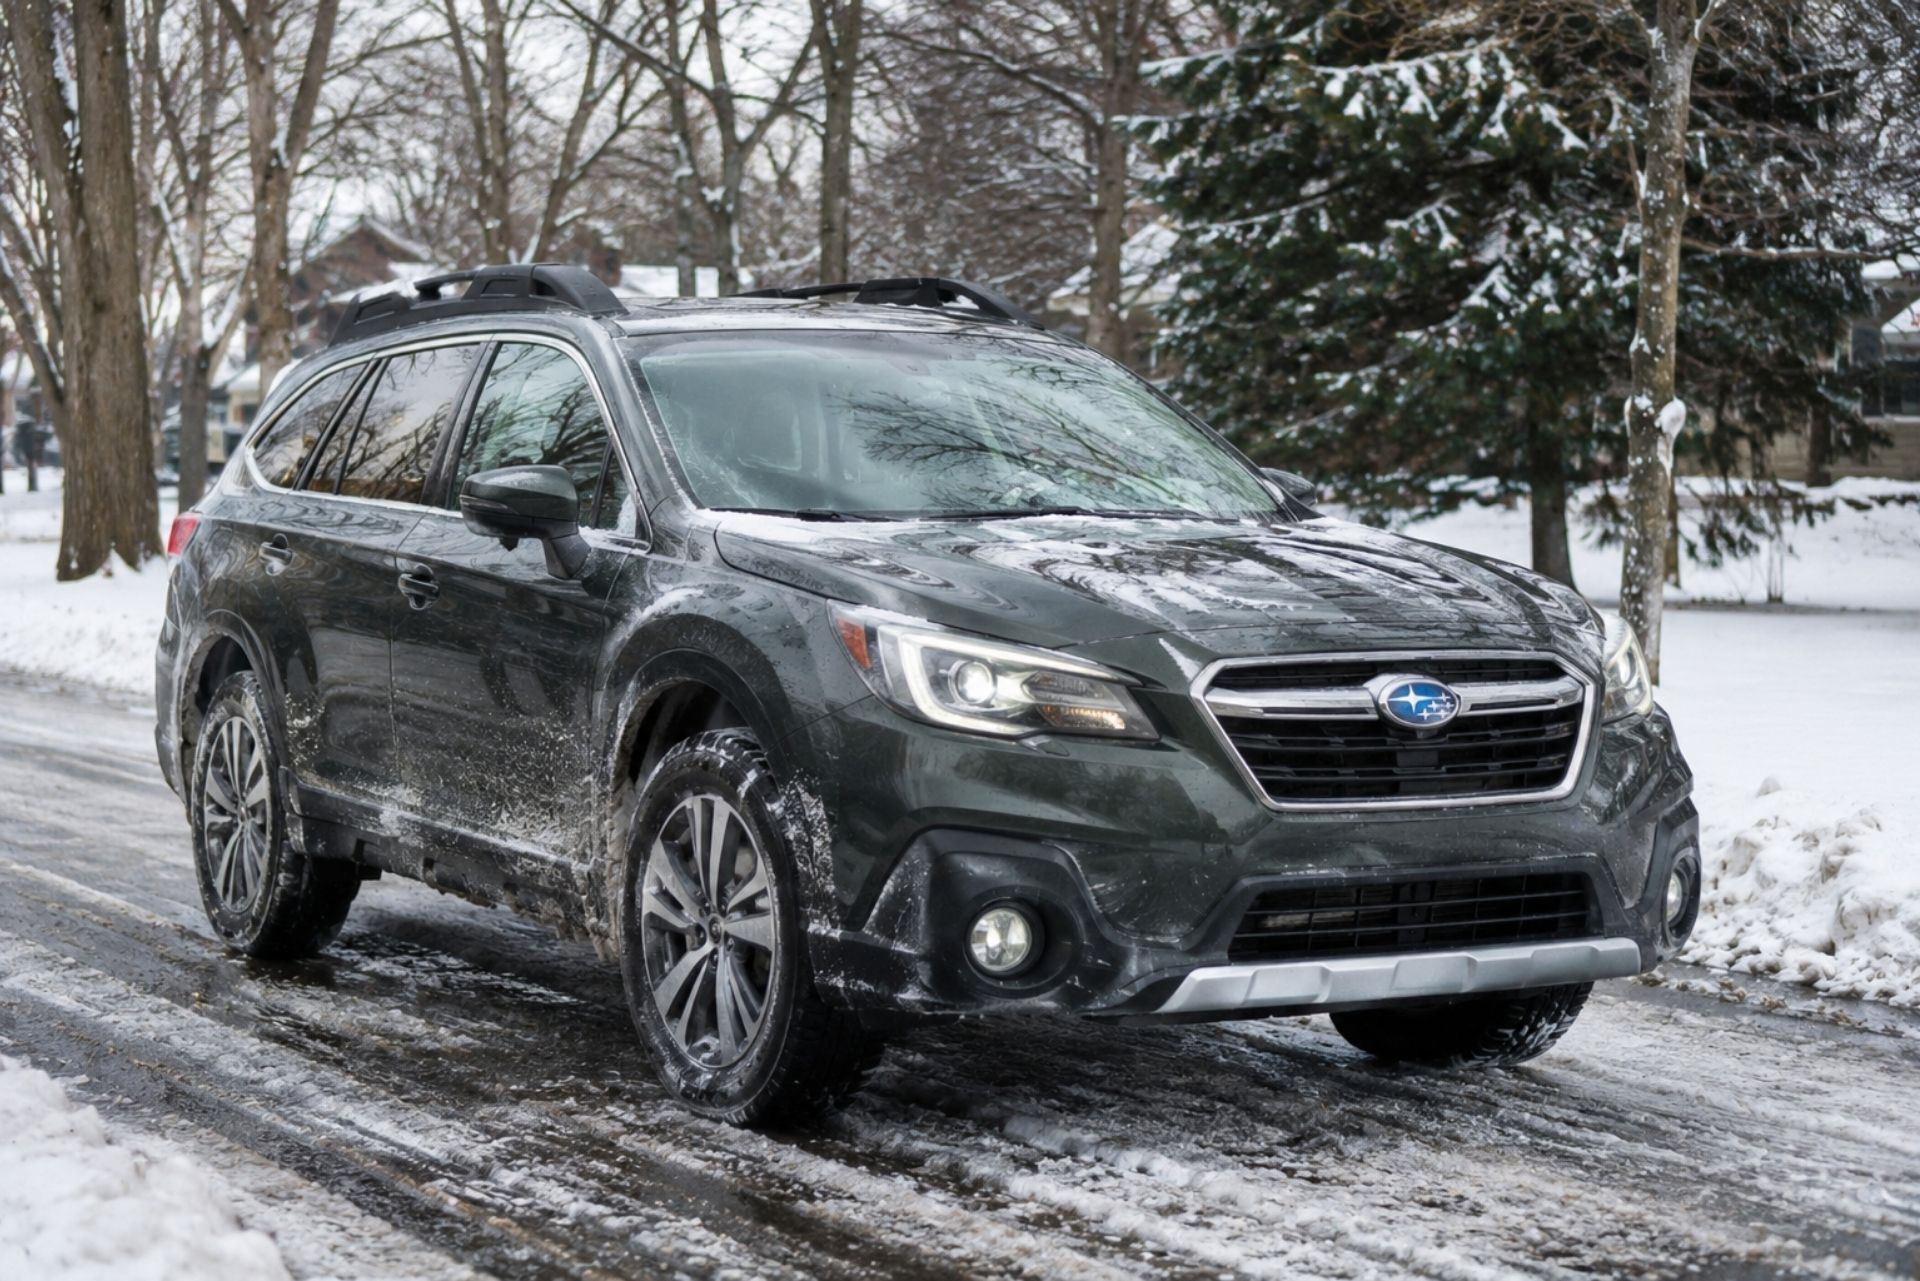
A Subaru Outback parked in a Grand Rapids driveway in January faces a very different set of risks than the same wagon sitting in a garage in Arizona. Michigan drivers deal with lake-effect snow, heavy deer traffic along rural highways, and the most distinctive no-fault auto insurance system in the country. Each of these factors shapes what your policy should include and what you will pay for it.
Insuring an Outback in Michigan is not simply a matter of buying the cheapest policy available. Your coverage has to account for the vehicle's all-wheel-drive system, its Eyesight driver assist cameras, and the state's Personal Injury Protection (PIP) choice levels. A well-built policy should protect you after a highway pileup on I-96 just as well as after a deer strike outside Traverse City.
This guide covers each part of that picture. It explains the PIP options available to Michigan drivers, how liability and collision coverage apply to an all-wheel-drive wagon, why windshield claims cost more than many owners expect, and which factors raise or lower your premium. The goal is to help you build tailored coverage for your Outback that holds up under real Michigan claim conditions.
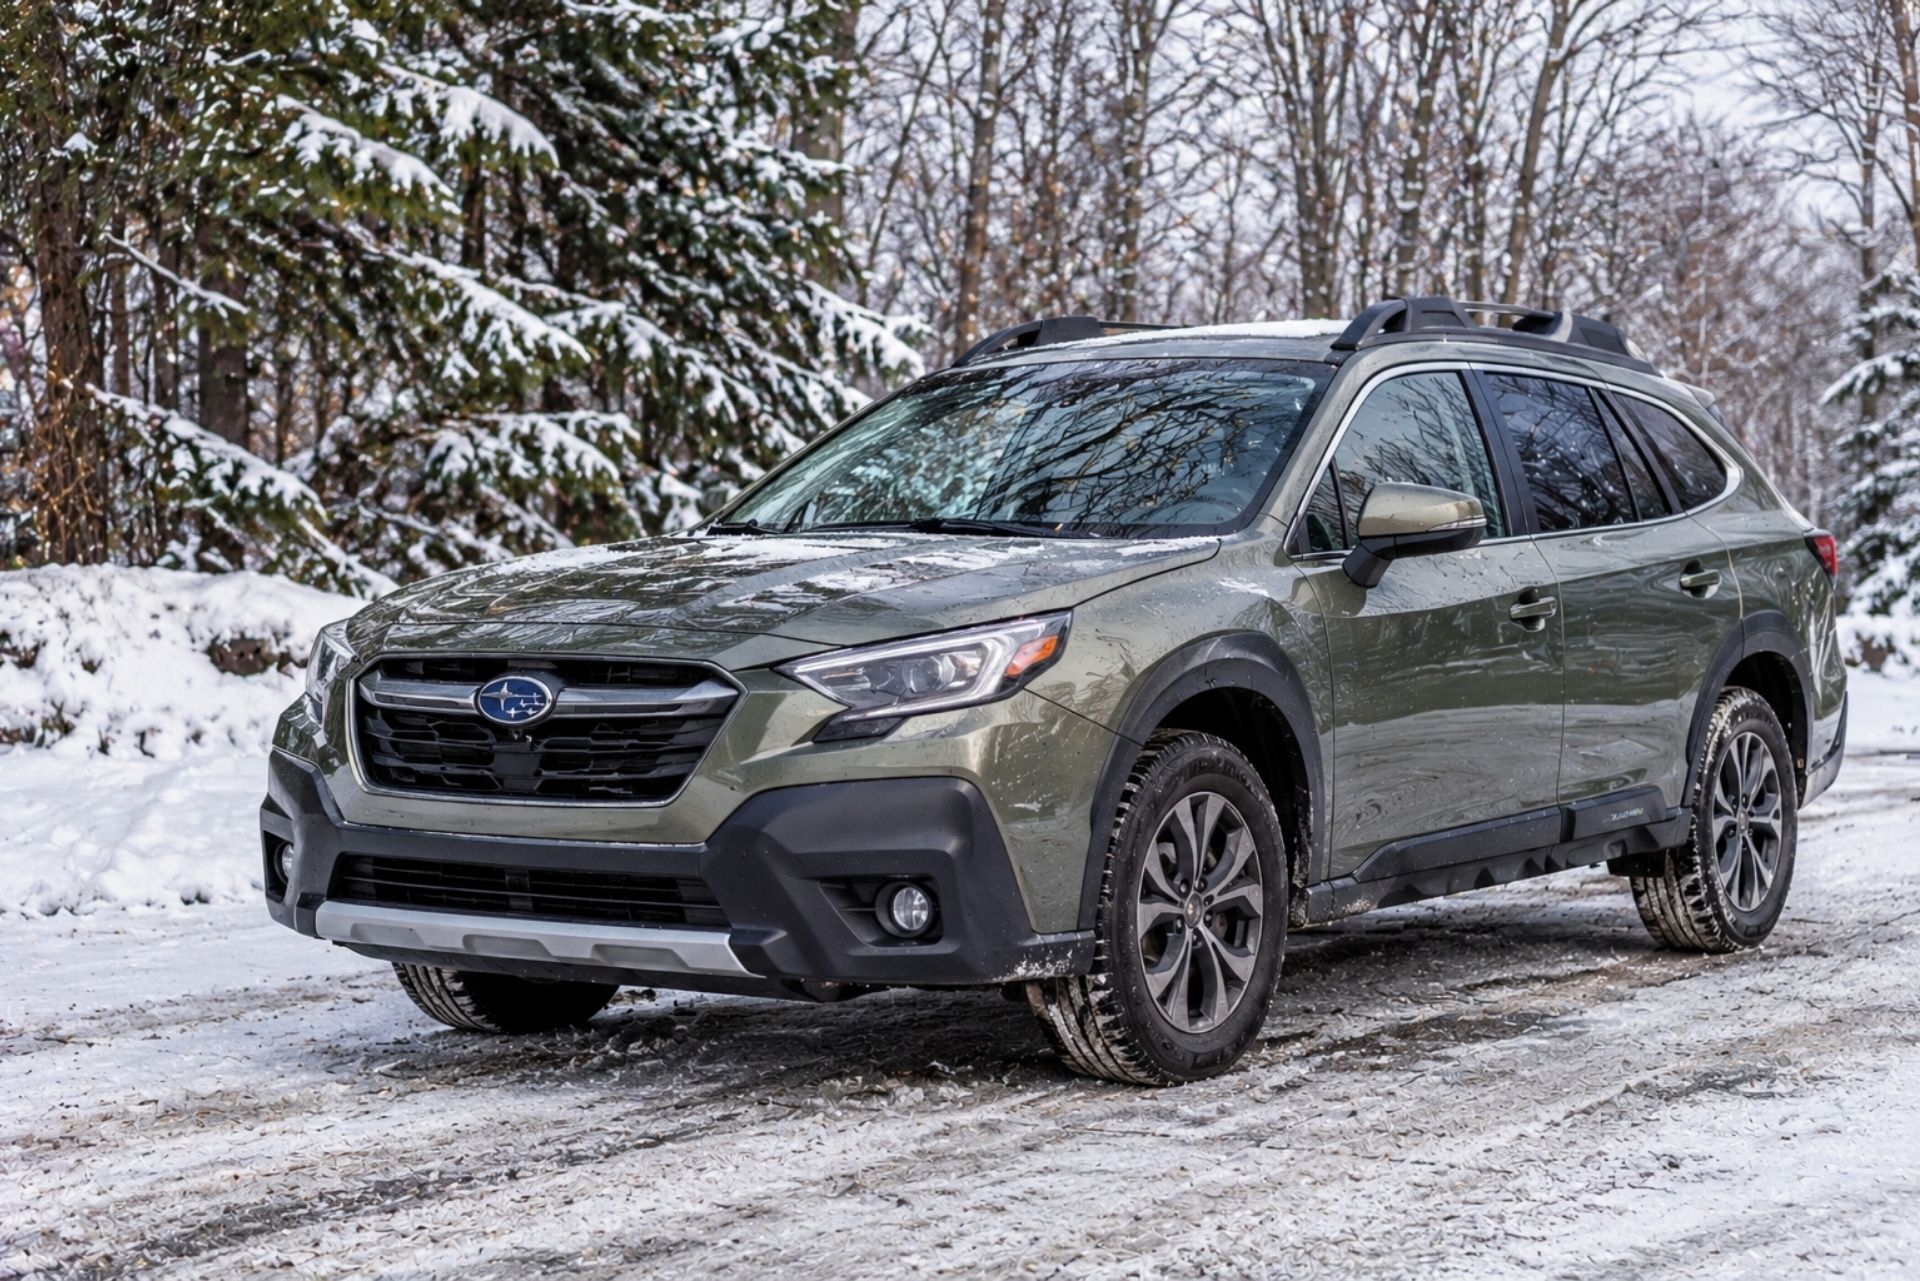
The Subaru Outback occupies a specific position in the Michigan insurance market. It is a family-oriented crossover wagon with standard symmetrical all-wheel drive, strong crash-test performance, and a driver base that insurers generally view as lower risk. These traits often work in your favor when underwriters price a policy.
The same features that make the Outback appealing also create specific claim patterns. Outback owners in Michigan tend to drive in poor weather because they trust the vehicle's traction, and they frequently travel rural roads to cabins, trailheads, and hunting areas Up North. That exposure produces a steady stream of comprehensive claims for deer strikes, cracked windshields, and storm damage.
Repair complexity is the other defining factor for Outback insurance in Michigan. Newer model years include camera-based Eyesight technology mounted behind the windshield, radar sensors in some trims, and an all-wheel-drive drivetrain that requires matched tires. A claim that looks minor on the surface can become expensive once calibration and drivetrain considerations enter the repair estimate.
Several characteristics shape how Michigan insurers view your Outback:
- Safety ratings: Strong crash protection can reduce injury-related claim costs.
- Driver assist systems: These may earn discounts but increase repair bills.
- Rural driving exposure: Higher likelihood of animal and road-debris claims.
- Winter usage: More miles driven in snow and ice than many other vehicles.
Understanding this profile allows you to build tailored coverage rather than relying on a generic policy. If you would like an independent review of your current Outback policy, a licensed Michigan agent can compare your coverage against these risk factors and prepare a quote.
By: John G. Growney
President of Oakland Insurance
Michigan's no-fault system requires your own insurer to pay medical expenses, lost wages, and certain replacement services after an auto accident, regardless of who caused the crash. This coverage is called Personal Injury Protection, and it remains the most significant cost driver on most Michigan auto policies. Since the 2019 reform took effect, you have had the ability to choose how much PIP medical coverage you carry.
That choice brings both savings opportunities and real risk. Selecting a lower PIP level can reduce your premium, but it can also leave you exposed if you suffer a catastrophic injury that requires long-term care. Many Michigan clients choose a level based on price alone without reviewing their health insurance, which is one of the most common and costly mistakes in the state.
Personal Injury Protection Choice Levels
Michigan offers several PIP medical tiers. You may select unlimited lifetime coverage, one of several capped coverage levels, a reduced tier available to drivers enrolled in Medicaid, or a full opt-out in certain circumstances. Drivers who have Medicare Parts A and B can opt out of PIP medical coverage entirely.
The opt-out carries a consequence that many drivers do not anticipate. The Michigan Court of Appeals determined that drivers who opt out are ineligible for benefits through the Michigan Assigned Claims Plan if injured as a pedestrian. If you walk near traffic in Ann Arbor or Lansing, that safety net may not be available to you, so the decision deserves careful review with an agent.
MCCA Assessments for 2024
The Michigan Catastrophic Claims Association (MCCA) reimburses insurers for very large PIP claims, and its per-vehicle assessment appears on your policy. The MCCA fee applies primarily to drivers who select unlimited PIP coverage, while lower tiers carry no assessment or a reduced one. The MCCA sets this assessment annually, and the figure set for the 2024 policy period has since been superseded, so you should confirm the current 2026 amount on your declarations page or with your agent before comparing quotes.
Liability and All-Wheel-Drive Considerations
Liability coverage protects you when you cause injury to another person or damage to their property. In Michigan, residual bodily injury liability applies when an injured party sues you for serious impairment or for damages that exceed no-fault benefits. Property protection insurance covers damage your Outback causes to properly parked vehicles, buildings, fences, and other property within Michigan.
All-wheel drive does not change the legal definition of liability, but it can influence how accidents occur. Outback drivers sometimes overestimate their stopping ability in snow because the vehicle accelerates so confidently. All-wheel drive helps with traction when moving forward, yet it does not shorten braking distances on ice, and rear-end collisions on slick roads remain a frequent source of liability claims.
Michigan's default bodily injury liability limits are higher than the minimums in many other states, and you must sign a specific form to select lower limits. Reducing these limits to save money is a decision that rarely makes sense for homeowners or business owners with assets to protect. A single serious injury claim from a multi-vehicle crash on US-23 can exceed low limits quickly, leaving your personal savings exposed.
Consider these liability recommendations for your Outback:
- Keep bodily injury limits at or above Michigan's default levels.
- Add an umbrella policy if you own a home, business, or significant savings.
- Review limits each year as your assets grow.
- Confirm that household drivers, including teenagers, are listed on the policy.
Contractors and tradespeople who use an Outback for job site visits should also confirm whether a personal policy covers that business use. A tailored
commercial or business-use endorsement may be necessary, and an agent can clarify your exposure during a brief consultation.
Collision and Comprehensive Coverage for the Outback
Collision and comprehensive are the two physical damage coverages that pay to repair or replace your own Outback. Collision covers damage from impacts with other vehicles or objects, while comprehensive covers theft, fire, hail, falling trees, flooding, and animal strikes. If you finance or lease your Subaru, your lender will almost certainly require both.
The distinction matters in Michigan because of deer. The state recorded more than 58,000 deer-vehicle collisions in 2025, with crashes peaking each fall. Hitting a deer falls under optional comprehensive coverage rather than collision, which surprises many drivers who assume any crash belongs under collision. If you swerve to avoid a deer and strike a guardrail instead, however, the claim typically becomes a collision claim.
Protecting Eyesight Driver Assist Technology
Subaru's Eyesight system relies on stereo cameras mounted near the top of the windshield, and many trims add radar and other sensors. These systems help prevent accidents, but they turn ordinary repairs into technical procedures. Recalibrating advanced driver assistance sensors after even a minor bumper impact can cost between $1,000 and $1,500, so your physical damage coverage should be strong enough to absorb that expense.
Standard vs. Broadened Collision Options
Michigan offers several collision options. Standard collision pays for damage regardless of fault, minus your deductible. Broadened collision waives your deductible when you are not substantially at fault, while limited collision pays only when you are not substantially at fault. For a newer Outback with expensive sensors, broadened collision often provides the strongest value because Michigan's mini-tort recovery has a cap that may not cover your full deductible and repair gap.
Michigan Coverage Comparison Table
The table below summarizes the core coverages discussed in this guide and how each applies to a typical Subaru Outback claim in Michigan. Use it as a quick reference when reviewing your declarations page or comparing quotes from different insurers.
| Coverage | Required in Michigan? | What It Pays For | Common Outback Claim |
|---|---|---|---|
| PIP Medical | Yes (level is your choice) | Your medical bills and related costs | Injuries in any crash |
| Bodily Injury Liability | Yes | Injuries you cause to others | Rear-end crash on ice |
| Property Protection | Yes | Damage to parked cars and property in Michigan | Sliding into a fence |
| Limited Collision | No | Your car, only if not at fault | Another driver hits you |
| Standard Collision | No | Your car, any fault, minus deductible | Single-car winter crash |
| Broadened Collision | No | Your car, deductible waived if not at fault | Struck while parked |
| Comprehensive | No | Deer, theft, hail, glass, fire | Deer strike in October |
The clearest value differences appear in the physical damage rows. Limited collision costs the least but leaves you paying for your own mistakes, while broadened collision costs more yet protects you from deductible expenses when another driver causes the damage. Comprehensive is optional by law, but given Michigan's deer population, very few Outback owners should go without it.
If any row in this table reveals a gap in your current policy, contact a Michigan agent to request a tailored quote that closes it before the next winter season.
Managing Winter Claims and Deductibles
Michigan winters produce a predictable cluster of claims: slide-offs into ditches, low-speed fender benders in icy parking lots, cracked windshields from road salt and gravel, and damage from ice-laden tree limbs. Your deductible choice determines how much of each claim you pay before insurance responds, so it deserves more thought than most drivers give it.
A higher deductible lowers your premium, but it only saves money if you can comfortably pay that amount after a claim. Many clients set a single high deductible across both collision and comprehensive, then discover that frequent glass and deer claims make a lower comprehensive deductible the better choice. Splitting deductibles, with a lower amount on comprehensive and a higher amount on collision, often fits Outback owners who drive rural roads.
Glass Repair and Windshield Calibration
Windshield replacement on an Eyesight-equipped Outback is not a simple glass swap. The stereo cameras must be recalibrated after replacement so the system reads lane lines and obstacles correctly, and that procedure adds meaningful cost. Ask whether your comprehensive coverage includes full glass protection, and confirm that your insurer allows repair shops to use glass compatible with Subaru's camera specifications.
How AWD Impacts Repair Costs
Subaru's symmetrical all-wheel drive requires all four tires to have closely matched tread depth, because significant differences can strain the drivetrain. If a pothole or curb strike destroys one tire, the repair shop may recommend replacing more than one tire or shaving a new tire to match. Drivers sometimes assume insurance will pay for all four tires, but coverage depends on the cause of loss and your policy language, so you should clarify this point before a claim occurs.
Michigan auto insurance costs remain among the highest in the country, though the 2019 reform gave drivers more control over the largest premium component. Your actual cost for an Outback depends on a combination of factors, and two drivers with identical vehicles can pay very different amounts. Rather than relying on a published average, which rarely matches any individual driver, focus on the variables you can influence.
The most significant factors include:
- PIP choice level: Lower medical tiers typically reduce your premium the most.
- Location: Detroit and its surrounding suburbs generally carry higher rates than Marquette or Holland.
- Driving record: At-fault accidents and violations raise rates for several years.
- Model year and trim: Newer trims with more sensors cost more to repair and insure.
- Deductibles: Higher deductibles lower premiums but increase out-of-pocket risk.
- Collision option: Broadened collision costs more than limited collision.
- Annual mileage: Long commutes increase exposure to winter and deer claims.
Discounts can offset part of these costs. The Outback's safety technology often qualifies Michigan drivers for advanced driver assistance discounts of up to 10%, depending on the carrier. Bundling home and auto coverage, paying in full, enrolling in paperless billing, and completing a usage-based driving program can produce further savings.
Keep in mind that the lowest premium is not always the lowest cost. A policy that saves you a modest amount each year but carries limited collision and a high comprehensive deductible can cost far more after a single deer strike and windshield calibration. An agent who reviews your full Subaru coverage can show you exactly where each dollar of premium goes and where savings make sense.
Common Questions About Insuring Your Outback
Does hitting a deer count as an at-fault accident in Michigan? A deer strike is filed under comprehensive coverage, and insurers generally do not treat it as an at-fault collision. Your comprehensive deductible will usually apply.
Can I skip PIP if I have good health insurance? Only drivers with Medicare Parts A and B can fully opt out of PIP medical coverage. Other drivers with qualifying health insurance may select a lower tier, but you should confirm that your health plan covers auto injuries first.
Will my insurance pay to recalibrate my Eyesight cameras? If the damage is from a covered claim, calibration is typically part of the repair cost. Ask your insurer in advance whether it covers calibration after glass-only claims.
Is broadened collision worth it on an Outback? For newer models with expensive sensors, broadened collision often pays for itself the first time another driver damages your car. Older, lower-value Outbacks may not need it.
Does all-wheel drive lower my insurance rate? All-wheel drive alone rarely produces a discount. Safety features and your driving record have a much larger effect on your premium.
Should I insure my Outback differently if I use it for work? Yes. Regular business use, such as visiting job sites, may require a business-use endorsement or a commercial policy.
Insuring an Outback well in Michigan comes down to matching each coverage to the risks you actually face. Your PIP level should reflect your health insurance and your exposure as a pedestrian, especially if you are considering a Medicare opt-out. Liability limits should protect the assets you have worked to build, and your collision option should account for the high cost of repairing sensor-equipped vehicles.
Comprehensive coverage deserves particular attention given the deer population and the cost of windshield calibration. Separate deductibles, full glass coverage, and broadened collision can turn a stressful winter claim into a manageable one. Discounts for driver assist technology and bundling can then help bring your total cost into balance.
Your next step is a coverage review before the next deer season or snowfall arrives. Contact a licensed Michigan insurance agent today, call or complete an online quote form, and request a tailored policy built around your Subaru Outback and the roads you drive every day.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying