Email us today!
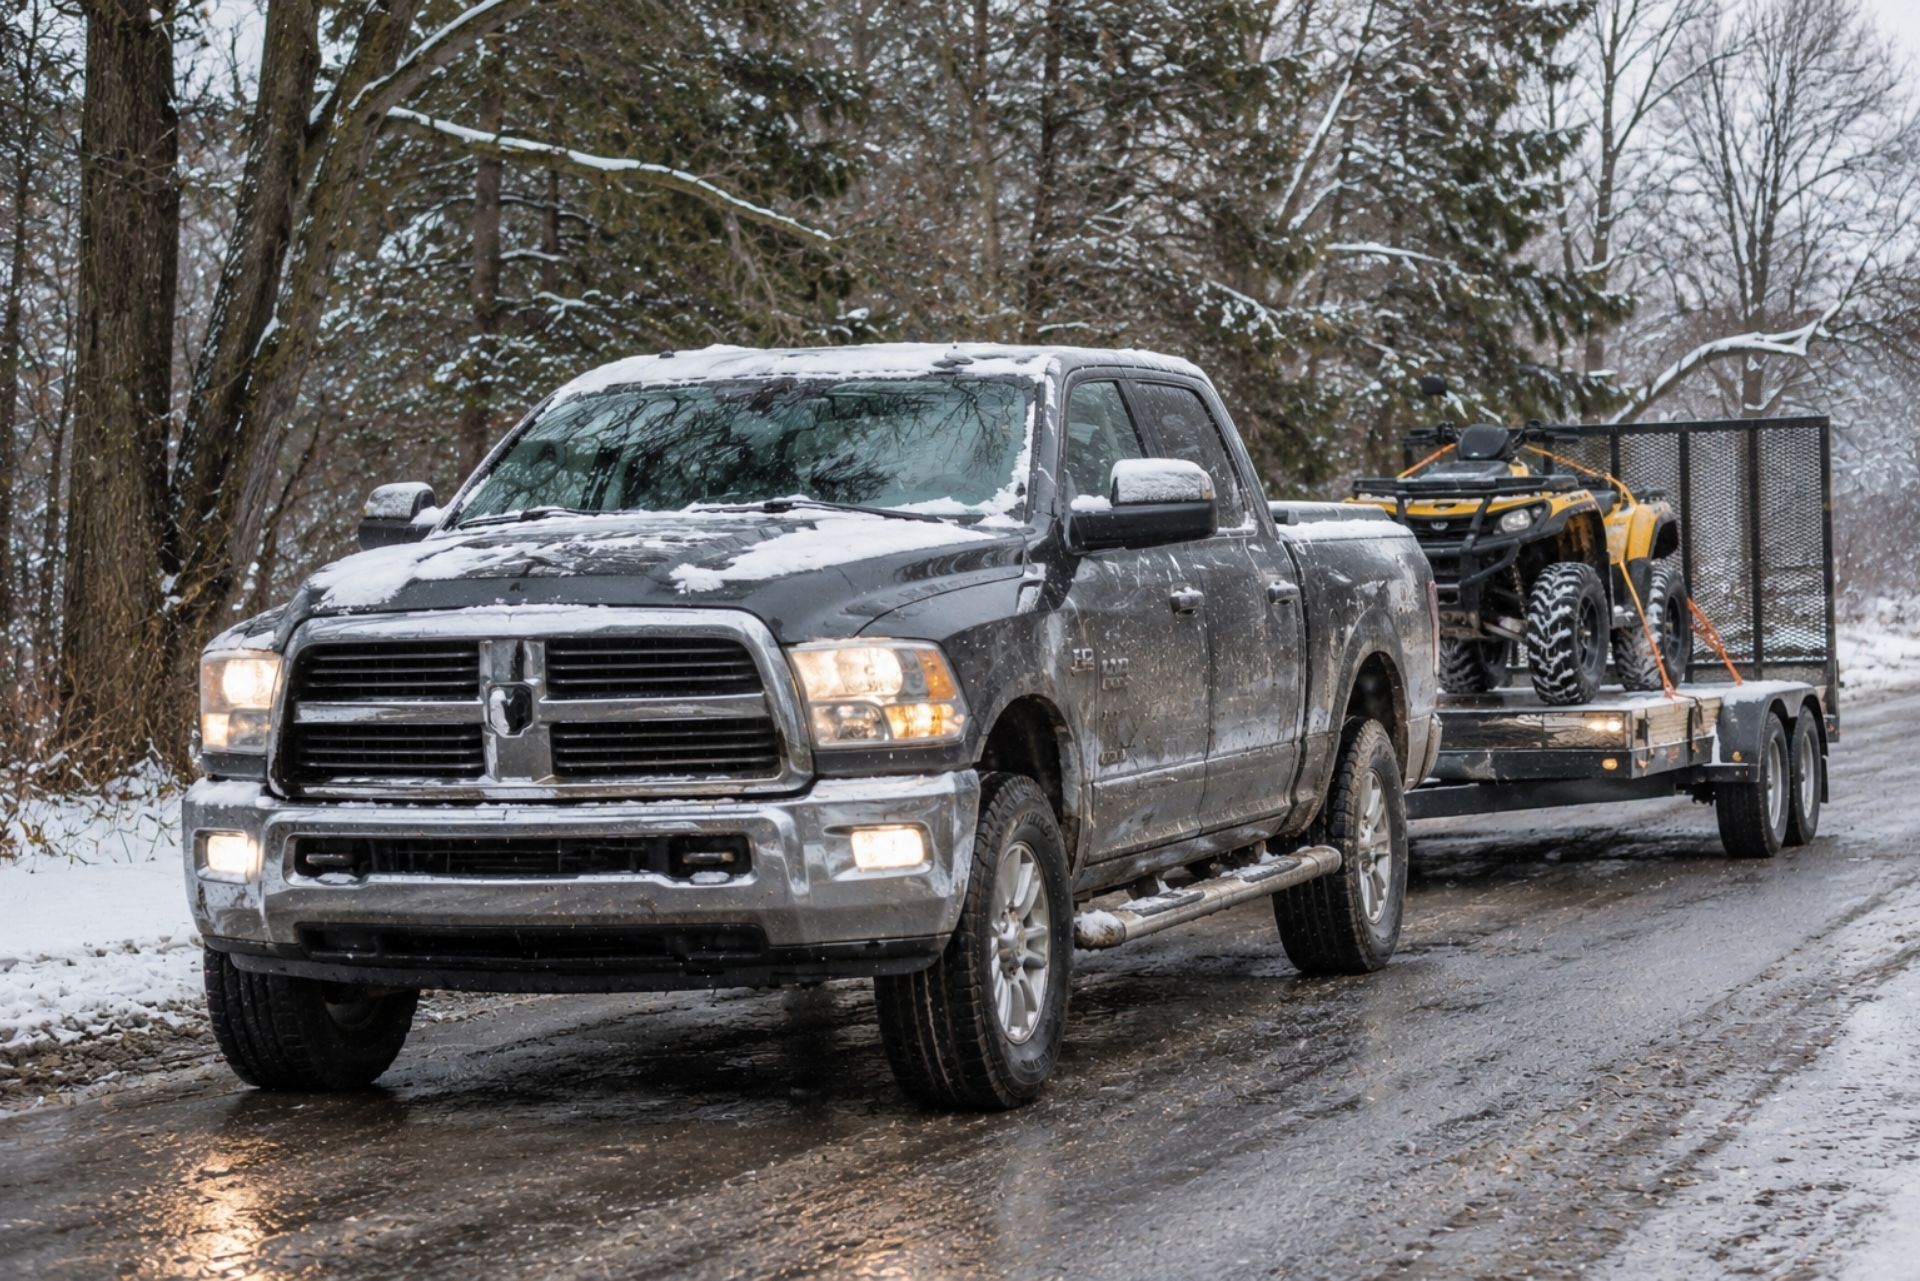
Picture a Grand Rapids contractor backing a loaded Ram 1500 out of a frozen job site in January, with a trailer of equipment hitched behind and a crew member riding along. One patch of black ice can turn that routine moment into a claim involving bodily injury, property damage, medical bills, and damaged tools. Michigan's no-fault system, its unique property protection rules, and the full-size truck's value all shape how your policy responds when something goes wrong.
Ram 1500 auto insurance in Michigan is not a simple commodity purchase. The truck often serves as a mobile office, a towing rig, and a family vehicle at the same time, and each role introduces different exposures. Contractors and tradespeople in Ann Arbor, Novi, Clarkston, and across the state frequently discover coverage gaps only after a loss, when it is too late to adjust.
This guide covers pickup truck liability, Michigan no-fault PIP, collision and comprehensive options,
towing and equipment protection, deductibles, and costs. The goal is to give you enough working knowledge to ask sharper questions and build a tailored policy that fits how you actually use your truck.
Every Ram 1500 registered in Michigan must carry three core coverages: residual bodily injury and property damage liability, personal injury protection (PIP), and property protection insurance (PPI). These are not optional add-ons. They form the legal foundation of any Michigan auto policy, and driving without them exposes you to fines, license consequences, and personal liability for an accident.
Michigan's default bodily injury liability limits are $250,000 per person and $500,000 per accident. You can formally waive these down to a $50,000/$100,000 floor by signing a selection form, but most advisors caution against it. A Ram 1500 weighs considerably more than the average sedan, and a serious collision with a smaller vehicle can generate injury claims that exceed lower limits quickly.
The catch is that liability for a work truck also intersects with your business. If you or an employee drive the Ram 1500 primarily for jobs, a personal auto policy may restrict or exclude that use. Discuss your actual driving pattern openly so your agent can determine whether a personal policy, a business-use endorsement, or a
commercial auto policy is appropriate.
By: John G. Growney
President of Oakland Insurance
Understanding Michigan No-Fault and Personal Injury Protection (PIP)
Michigan's no-fault system means your own policy pays your medical expenses, lost wages, and certain replacement services after an accident, regardless of who caused it. PIP is the coverage that delivers these benefits, and it remains one of the main reasons Michigan premiums differ so sharply from neighboring states.
Medical costs inside the system are also rising. Michigan's auto insurance medical provider fee schedule received a 16.38% cumulative increase for services rendered between July 2, 2026, and July 1, 2027. This matters because higher reimbursement rates can push PIP claim costs upward, which eventually influences what carriers charge for that coverage.
PIP Medical Options and Cost Savings
Michigan drivers choose among several PIP medical levels: Unlimited, $500,000, $250,000, or a $50,000 option available to Medicaid recipients. Some drivers with qualifying health coverage may opt out of PIP medical entirely. Each step down typically lowers your premium, but it also shifts more financial risk onto you or your health plan.
Opt-out rules may change. Senate Bill 1208, introduced in October 2026, proposes raising the health-plan deductible cap for PIP opt-out eligibility from $6,000 to $6,579. A common mistake is choosing a lower PIP level without confirming that your health insurance actually covers auto accident injuries, so check that exclusion before you sign.
Property Protection Insurance (PPI) for Truck Owners
PPI pays for damage your Ram 1500 causes to other people's property within Michigan, such as buildings, fences, mailboxes, and properly parked vehicles. For contractors maneuvering a full-size truck around tight residential driveways and commercial lots, this coverage responds to some of the most frequent claims we see. PPI does not cover damage to your own truck, which is where collision coverage becomes essential.
Protecting Your Investment: Collision and Comprehensive Coverage
A newer Ram 1500 represents a substantial investment, and lenders almost always require collision and comprehensive coverage until the loan is paid off. Even after payoff, many owners keep both because repairing a modern truck's sensors, cameras, and body panels is expensive.
Comprehensive coverage handles non-collision losses: theft, vandalism, hail, falling trees, flooding, and deer strikes. Deer collisions are a persistent Michigan risk, especially on rural roads in the fall, and they fall under comprehensive rather than collision on most policies. Collision coverage pays to repair your truck after an impact with another vehicle or object.
Safety ratings deserve your attention as well. The 2025-2026 Ram 1500 Crew Cab received a "Poor" rating in the updated moderate overlap front crash test because the rear passenger dummy showed a high risk of chest and abdominal injuries from seatbelt submarining. If you regularly carry crew members in the back seat, that finding strengthens the case for higher PIP and liability limits.
Choosing Between Standard, Broadened, and Limited Collision
Michigan offers three distinct collision options, which few other states provide:
- Limited collision: Pays only when you are not substantially at fault, with no deductible. It is the least expensive but leaves you unprotected if you cause the accident.
- Standard collision: Pays regardless of fault, but your deductible always applies.
- Broadened collision: Pays regardless of fault, and waives your deductible when you are not substantially at fault.
For a financed Ram 1500 used daily on job sites, broadened collision often provides the most balanced, tailored protection.
Insuring Towing Gear and Aftermarket Equipment
Many Ram 1500 owners in Michigan add lift kits, tonneau covers, light bars, upgraded wheels, toolboxes, and hitch systems. Standard auto policies typically cover only factory-installed equipment, so aftermarket parts may receive little or no reimbursement after a theft or total loss unless you schedule them with custom equipment coverage.
Tools and business equipment are a separate issue entirely. A personal auto policy generally does not cover the contents of a truck bed, such as saws, generators, or ladders. Contractors usually need an inland marine or tools and equipment policy to protect those items, whether they are stolen from the truck in Detroit or damaged in a rollover near Traverse City.
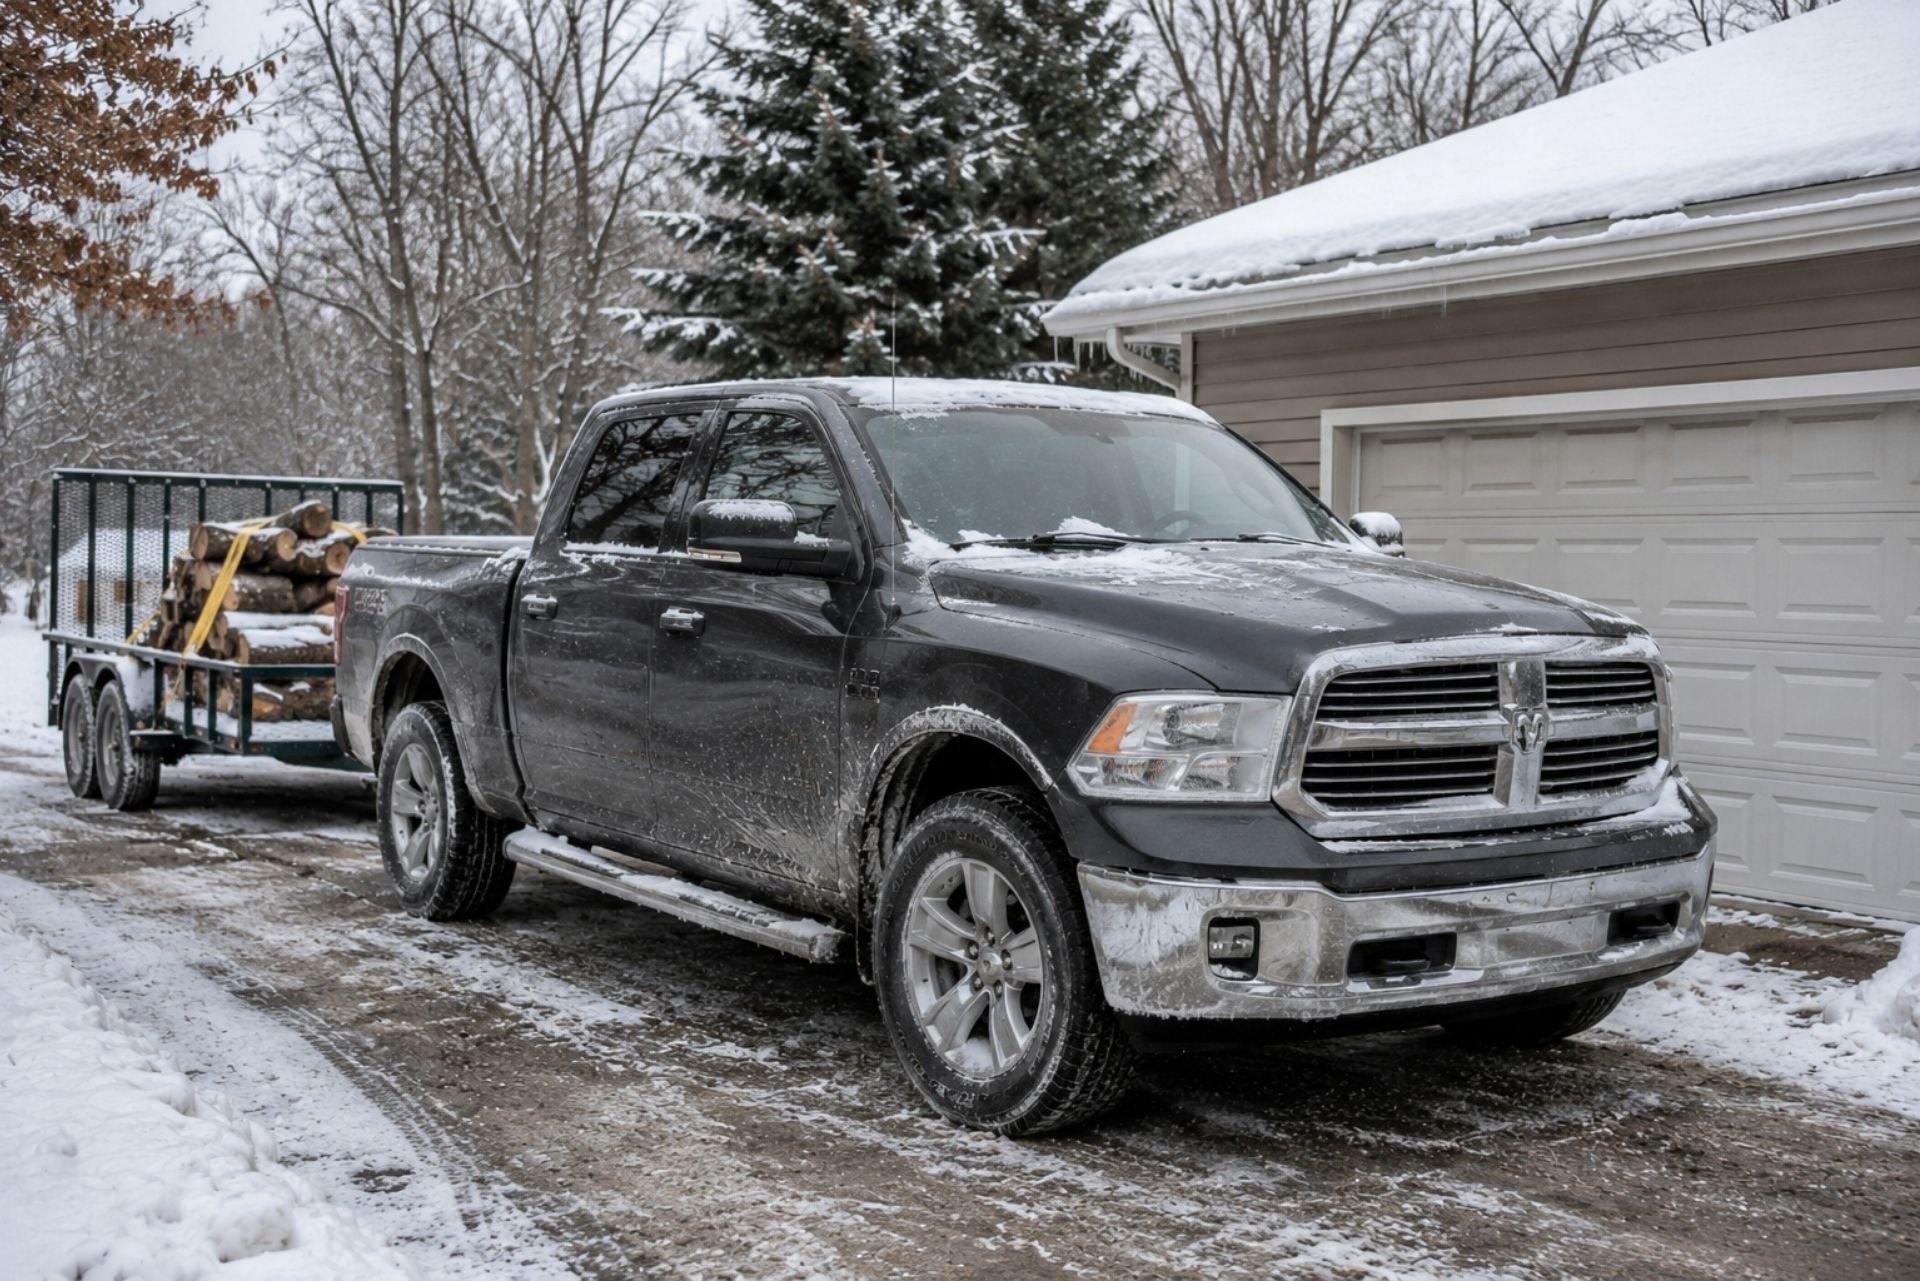
Trailers also require attention. Liability often extends to a trailer attached to your Ram 1500, but physical damage to the trailer itself may require separate coverage. New Ram 1500 trucks typically include manufacturer roadside assistance for 5 years or 60,000 miles, so review whether a towing and labor endorsement duplicates that benefit before paying for it. Mechanical issues are worth tracking too: a
class-action lawsuit filed in August 2026 alleges the Hurricane engine has a defective control module that causes sudden power loss, which reinforces the value of dependable roadside coverage.
Comparing Coverage Levels and Deductible Impacts
Your deductible choices directly shape both your premium and your out-of-pocket exposure after a claim. Raising your comprehensive and collision deductibles usually reduces your premium, but you must be prepared to pay that amount on short notice, perhaps in the middle of a busy construction season.
The table below compares common coverage approaches for a Ram 1500 owner in Michigan.
| Coverage Element | Minimum Approach | Balanced Approach | Maximum Protection |
|---|---|---|---|
| Bodily Injury Liability | $50,000/$100,000 (waived) | $250,000/$500,000 | Higher limits plus umbrella |
| PIP Medical | Opt-out or lowest eligible | $250,000 or $500,000 | Unlimited |
| Collision Type | Limited | Standard | Broadened |
| Deductibles | High | Moderate | Low |
| Custom Equipment | None | Scheduled major items | Full aftermarket schedule |
| Premium Level | Lowest | Moderate | Highest |
One thing to keep in mind: the cheapest configuration often costs the most after a serious loss. A contractor who drops to minimum liability and limited collision might save on premiums, then face personal exposure for an injury lawsuit plus full repair costs for an at-fault accident. Costs vary widely by ZIP code, driving record, and credit-based factors, so request quotes at several deductible levels to see the real tradeoff for your situation.
Common Questions About Insuring a Ram 1500 in Michigan
Is a Ram 1500 expensive to insure in Michigan? Premiums depend on your location, driving history, trim level, and PIP choice. Full-size trucks with advanced electronics often cost more to repair, which can raise collision and comprehensive rates.
Do I need commercial auto insurance if I use my Ram 1500 for work? If the truck is titled to your business or used primarily for jobs, you likely need commercial coverage. A personal policy may deny claims tied to business use.
Does my policy cover tools stored in my truck bed? Usually not. Tools and equipment generally need a separate inland marine or contractor's equipment policy.
What happens if I hit a deer with my Ram 1500? Deer strikes are typically covered under comprehensive, not collision. Your comprehensive deductible applies.
Can I lower my premium by choosing a smaller PIP limit? Yes, lower PIP levels usually reduce premiums. Confirm that your health insurance covers auto accident injuries first.
Does Michigan require collision coverage? State law does not require it, but your lender almost certainly will if your truck is financed or leased.
Making the Right Choice for Your Pickup
Insuring a Ram 1500 in Michigan means balancing state-mandated coverages with protection that reflects how you really use the truck. Strong liability limits guard your personal and business assets, while your PIP selection determines how medical bills are handled after an accident. Choosing the right collision type, scheduling aftermarket equipment, and covering tools separately close the gaps that most often surprise truck owners at claim time.
Your path forward is straightforward:
- List how you use the truck, including job sites, towing, and passengers.
- Confirm your health plan's auto accident coverage before selecting PIP.
- Inventory aftermarket parts and tools with receipts.
- Compare quotes at two or three deductible levels.
A tailored policy built around these details protects your Ram 1500, your crew, and your livelihood across every Michigan season. Call our office or fill out our online form today to schedule a consultation and receive a quote designed for your pickup.
About The Author:
John G. Growney
As President of Oakland Insurance, I bring over 25 years of experience in every aspect of the insurance industry — from customer service to sales and agency management. As a Licensed Insurance Counselor (LIC) and Certified Insurance Counselor (CIC), I’m dedicated to helping clients make confident decisions about their coverage. I earned my B.A. in Business from Michigan State University and currently live in Clarkston, Michigan with my two children and our rescue dogs.
Contact Us Page
Your Business Insurance Solutions
Workers Comp Insurance

Workers' compensation insurance is a type of insurance that provides benefits to employees who are injured or become ill as a result of their job. These benefits may include medical expenses, lost wages, and disability payments.
COMMERCIAL AUTO INSURANCE
Commercial auto insurance is a type of insurance that covers vehicles used for business purposes. This includes cars, trucks, vans and other vehicles owned by a company and used by employees for work-related activities.
PROFESSIONAL LIABILITY
Professional liability insurance, also known as errors and omissions insurance, is a type of insurance that protects businesses and individuals from financial losses resulting from claims of professional negligence or failure to perform professional duties.
BUSINESS OWNERS POLICY (BOP INSURANCE)
Business Owners Policy (BOP) insurance is a package policy that combines general liability insurance and property insurance for small and medium-sized businesses. It is designed to provide coverage for common risks such as property damage, liability claims, and business interruption.
Our Process
Oakland Insurance has an efficient, customer-focused approach when working with business owners looking for business insurance in Michigan.
1. Consultation
This begins from the moment a business owner reaches out for business insurance. Our business mindset helps us approach every consultation process as an opportunity to learn about a business and its needs, so we can recommend the best business insurance coverage that fits their situation.
2. Insurance Options
We take pride in our attention to detail: from fine-tuning insurance plans to contacting multiple competing carriers, we ensure our clients receive effective business insurance solutions tailored to their unique goals and operations.
3. Claims
We know that the claims process can be complex and time-consuming. That’s why Oakland Insurance works with clients to file and track their claims quickly and efficiently, so they can get back to running their businesses with minimal disruption.
4. Customer Service
Oakland Insurance provides ongoing support and advice to clients who have questions about their business insurance policies or need additional coverage. Our experienced team is dedicated to helping our clients make informed decisions regarding their commercial insurance needs.
Contact us today to get started!
Industries Served In Michigan
Electrician
Insurance
Electricians typically need liability insurance to protect themselves from claims of property damage or bodily injury caused by their work.
Contractor Insurance
General contractors typically need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Carpenters Insurance
Carpenters may need workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Auto Dealer
Insurance
Automobile dealer's may need physical damage insurance to cover damages to the vehicles on their lot and garage liability insurance to cover any injuries that occur on their premises.
Commercial Buildings Insurance
Commercial building owners typically need property insurance to protect their building and contents from damage or loss due to covered perils such as fire or theft.
Hotel & Motel Insurance
Hotels & Motels typically need may also need liability insurance to protect themselves from claims of bodily injury or property damage caused by their operations, and workers' compensation insurance to cover medical expenses and lost wages for any on-the-job injuries.
Cost of Business Insurance in Michigan
The cost of business insurance in Michigan can vary depending on a number of factors, including the type of business, its size, location, and the level of coverage needed. Some of the most common types of business insurance policies in Michigan include general liability insurance, property insurance, workers' compensation, and professional liability insurance.
General liability insurance is typically required for most businesses and can protect against claims of bodily injury or property damage caused by your business operations. The cost of this coverage can range from a few hundred dollars per year for a small business to several thousand dollars per year for a larger business.
Property insurance is another important type of coverage for businesses in Michigan and can protect against damage to buildings, equipment, and inventory. The cost of this coverage can vary depending on the value of the property and the level of protection needed.
Workers' compensation is mandatory for most businesses in Michigan and can protect against claims made by employees who are injured or become ill as a result of their work. The cost of this coverage is typically based on the number of employees and their salaries.
Professional liability insurance is often required for businesses that provide professional services, such as consulting or legal advice. This type of coverage can protect against claims of negligence or errors and omissions. The cost of this coverage can vary depending on the type of business and the level of protection needed.
Overall, the cost of business insurance in Michigan can vary widely depending on the specific needs of the business. It is important to work with a reputable insurance agent who can help you determine the right coverage for your business and provide you with competitive quotes.
Why Choose Us
Oakland Insurance offers comprehensive small business liability insurance in Michigan. Our experienced team will take the time to understand a client’s needs and provide tailored solutions that meet their unique requirements.
We offer competitive rates and have access to numerous carriers, so we can work with our customers to help them get the best coverage for their budget. Our commitment to providing exceptional customer service means we are always available for advice and support when needed.
Testimonials
What Our Commercial Insurance Clients Are Saying